Geomechanics, Streamlined.
© 2026 Geomechanics.io. All rights reserved.
Caterpillar’s R2900 XE diesel-electric LHD has been deployed since September 2026 at K+S’s Borth rock salt mine in Rheinberg, North Rhine-Westphalia, loading and hauling ore to underground tipping points. The Borth operation, the last active mine on the Lower Rhine, produces about 2.4 Mt/y of mined salt, giving Caterpillar a high-volume industrial minerals reference site for the R2900 XE. For engineers, the trial offers data on diesel-electric performance, availability and energy use in continuous salt mining conditions.
China’s REBIO Group, led by Vice President Weijia Jiang and its Mining Wear Parts Division chief expert, has engaged HBIS Group Mining’s Sijiaying Iron Ore Mine in detailed engineering talks on customised crusher wear solutions tied to specific ore characteristics and maintenance regimes. The team focused on optimising liner profiles, alloy selection and wear-life prediction for high-throughput primary and secondary crushers, aiming to cut unplanned shutdowns and stabilise product size. Similar advanced wear strategies are being developed for the Simandou iron ore project, signalling tighter integration of metallurgy, wear modelling and mine planning.
EACON reports that its first-half 2026 results show a gross profit margin of 18.9%, up 17.2 percentage points year-on-year, as it shifts to a more scalable, asset-light model for autonomous haulage system (AHS) deployment. The company positions this stronger financial capacity to support wider rollout of its AHS solutions across multiple mine sites without owning large truck fleets, focusing instead on software, control platforms and integration services. For mine operators, this signals growing availability of third-party AHS provision with lower upfront capital tied to mobile equipment.
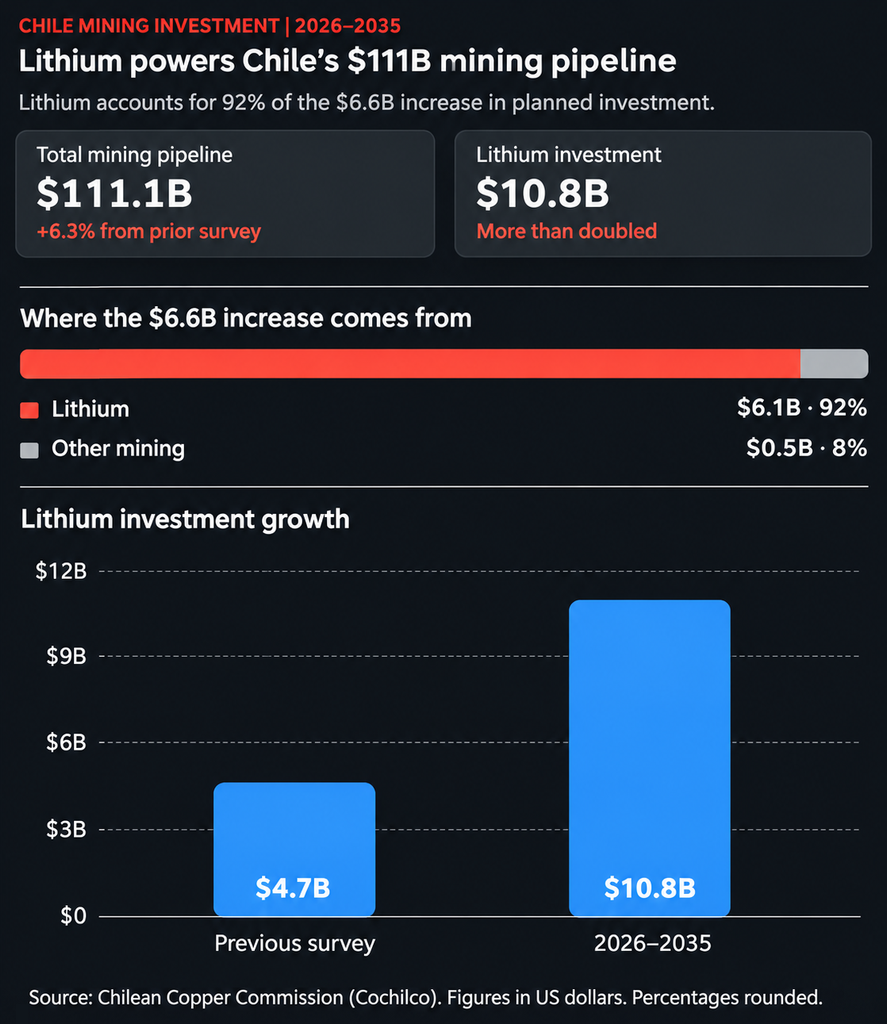
Chile’s mining investment pipeline has climbed to $111.1 billion for 2026–2035, with lithium projects doubling to $10.8 billion and two DLE-based schemes — Albemarle’s $3.1‑billion conversion and the $3‑billion Salar Futuro JV between Codelco and SQM — now awaiting SEA environmental approval. Copper still dominates at $93.9 billion, including BHP’s $1.3‑billion Escondida leaching extension to sustain 210,000 t/y cathode output and Capstone’s $500‑million Mantos Blancos upgrade to 9.8 Mt/y sulphide throughput. Antofagasta alone hosts $51.5 billion of projects, intensifying pressure on housing, services and transport corridors such as the Capricorn Bioceanic Corridor.
The US government has issued its first commercial deep-sea mining leases in more than 60 years, granting Wetstone US Ventures two 20‑year blocks covering about 31.5 million acres off American Samoa for a total of $6 million, despite a federal court ruling that regulators had not fully assessed impacts on endangered whales, sea turtles and coral. Three lawsuits led by Earthjustice, Finafinau and the Natural Resources Defense Council challenge both the environmental review and federal authority under the Outer Continental Shelf Lands Act and historic Samoan treaties. Wetstone may begin seafloor surveys and exploration but must secure further approvals before any commercial extraction, while additional seabed auctions are being considered off the Northern Mariana Islands, Virginia and Alaska.
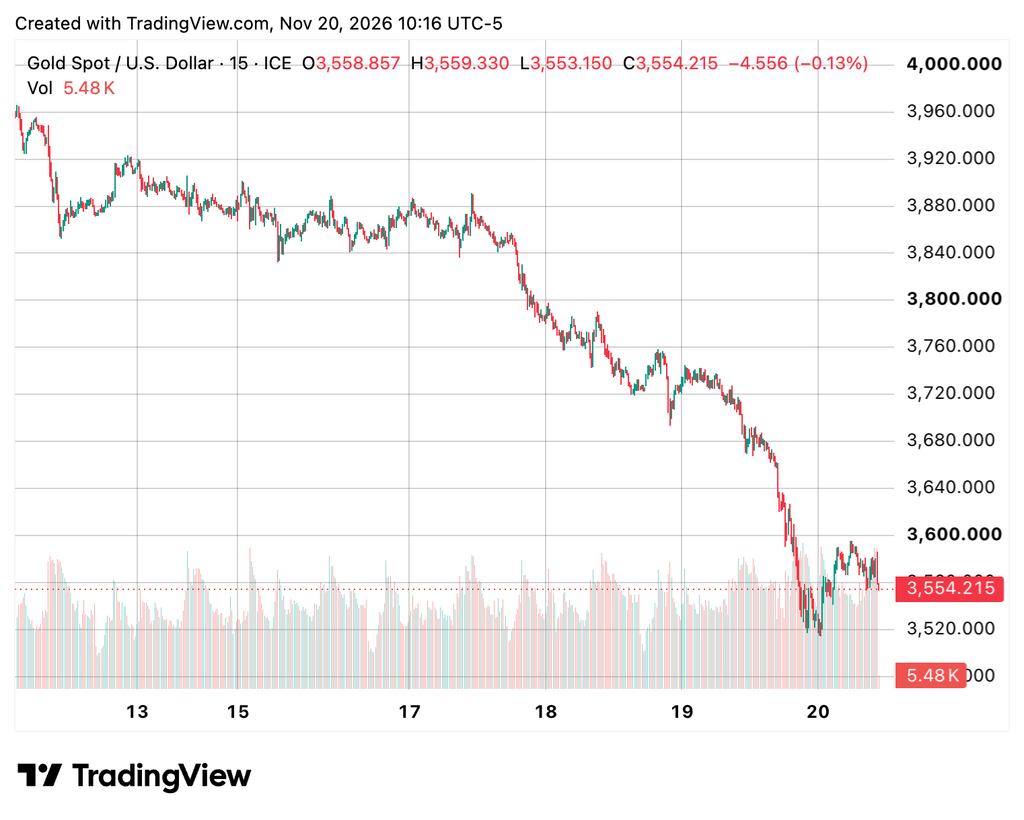
Gold fell towards $3,500 per oz. on expectations of a December US rate hike, while miners’ all-in sustaining costs jumped 22% year-on-year in Q2 to $1,930 per oz., driven largely by record sustaining capex of $441 per oz., up 34% quarter-on-quarter. Margins above AISC slipped 16% to $2,582 per oz., with Barrick’s realised price dropping $174 per oz. in Q3 as its AISC rose to $1,911 per oz., and B2Gold’s Goose mine in Nunavut reporting extreme Q2 AISC of $6,390 per oz. after a crushing-circuit fire. Agnico Eagle still plans more than $3.5 billion in 2027 capital spending, including $96 million at Detour Lake in Q3, signalling large producers are not yet deferring major projects despite cost pressure.
Modern Mining Technology plans an 18‑month build‑out of its first commercial e‑waste metals recovery hub in North Carolina, targeting 40,000 gold‑equivalent ounces per year using an aqueous-based process fed by a one‑tonne‑per‑hour waste printed circuit board pre‑concentration plant. Backed by a US$40‑million IPO on 12 November and a pilot facility in Greenville that has shipped 41 concentrate lots since late 2023, the company claims metal grades around 100 times typical mined ore. Its hub‑and‑spoke design allows multiple pre‑concentration plants near e‑waste suppliers to feed a central purification plant, with R2 Standard certification pursued.
Angola plans to invest about $180 million for a 10% stake in De Beers via state miner Endiama, implying a $1.8 billion equity valuation that sits well above the roughly $1.18 billion suggested by the Global Diamond Consortium’s reported $1 billion offer for Anglo American’s 85%. The move would place Angola alongside Botswana, which aims to lift its holding from 15% to 30%, and Namibia in a producer-led ownership bloc as natural diamond demand weakens and lab-grown competition grows. Endiama CEO José Manuel Augusto Ganga Júnior also confirmed commissioning of Angola’s first gold refinery in Luanda, designed to process 25 kg of gold per day to support in-country beneficiation.
Copper futures have fallen into bear-market territory just ten weeks after hitting a record, with Comex December contracts down 20.2% from the 9 September peak of $6.8885/lb and shedding more than 9% this week, while LME three‑month prices slid to $12,020/t, 18% below their recent high. The selloff, driven by unwinding AI‑boom bets, a stronger dollar and fading US tariff expectations, has erased 2026 gains and wiped about $127 billion (15%) off the market value of 11 major copper‑exposed miners, including a 22% weekly drop for Freeport‑McMoRan. In contrast, Chinese physical tightness has pushed Yangshan import premiums to a record $500/t, triggering shipments of tens of thousands of tonnes from swollen US inventories and prompting Codelco to offer 2027 cathode at $250–$280/t to Chinese buyers.
Pakistan’s drive to “mine in Pakistan, process in Pakistan, manufacture in Pakistan” risks building copper smelters ahead of secure mine supply, with only Saindak producing and Reko Diq still ramping towards exporting concentrate via rail to Port Qasim and the Pakistan International Bulk Terminal. Global smelting economics are hostile, with 2026 benchmark treatment and refining charges at $0/t and spot terms as low as –$47.40/t, while Adani’s $1.2‑billion Kutch Copper plant has reportedly secured just over 25% of its 1.6 Mt/y feed requirement. Exploration is further constrained by taxes and customs duties consuming about 30% of exploration budgets, even as Punjab’s Khushab mineral processing zone offers 15‑year nominal‑rent land and duty concessions to downstream investors.
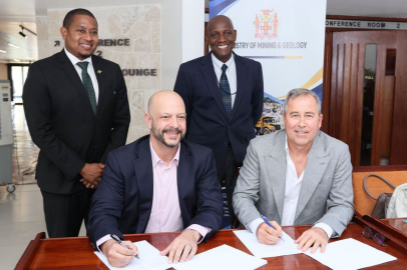
ElementUSA has signed an MOU with Geophysx Jamaica Limited to pilot processing of Jamaica’s extensive bauxite residue deposits into critical minerals and pig iron, using recovery technology proven at ElementUSA’s Critical Resource Accelerator in Cedar Park, Texas, which is backed by the US Departments of War and Energy. The pilot, to be run at new and existing Jamaican facilities, will feed into feasibility studies and the design of a commercial-scale plant, subject to financing and regulatory approvals. Geophysx will provide licensed access to residue sites and manage local stakeholder engagement, aiming to convert long‑standing red mud storage areas into a new, Jamaican‑led industrial sector.
Macmahon Holdings’ subsidiary PT Macmahon Indonesia has been named preferred contractor by PT Freeport Indonesia for underground construction at the Kucing Liar Underground Mine Complex in Papua. The package covers fixed facilities across three underground levels, including heavy-equipment maintenance workshops, refuelling stations, wash bays and multiple pump stations integrated into the mine’s existing infrastructure. The works point to substantial underground services demand and long-term contractor presence as Kucing Liar ramps up alongside the Grasberg Block Cave operations.
Orica has confirmed it is in Stage 2 of a competitive sales process to acquire Syensqo’s Technology Solutions unit, a mining-focused subdivision of Syensqo’s chemicals business. The unit supplies process and reagent technologies to mineral processing operations, positioning Orica to extend its portfolio beyond blasting and ground support into higher-margin, plant-level chemistry and digital process optimisation. Any deal would deepen Orica’s integration across the mine-to-mill value chain, with implications for how sites source specialty reagents, technical support and performance-based chemical contracts.
BME, a subsidiary of Omnia Holdings, has opened Western Australia’s first electronic detonator manufacturing plant in Kalgoorlie to locally supply its AXXIS electronic initiation systems to hard-rock mines. The facility is positioned close to the Eastern Goldfields’ large open-pit and underground operations, reducing lead times and import dependence for precision-timed blasts. For drill-and-blast engineers, local production should improve security of supply for electronic detonators and allow tighter integration of blast design with BME’s digital planning and blast control tools.
Spartan Metals’ Victorio project in New Mexico carries a US$683 million initial capex for an underground block-cave tungsten–molybdenum mine and ammonium paratungstate plant, with a 24-year life and a further US$2.03 billion sustaining capital. The PEA pegs after-tax NPV at US$2.14 billion (8% discount) and IRR at 31%, based on annual output of about 4,100 tonnes tungsten trioxide (as APT) and 8.65 million lb molybdenum, from 76.7 Mt measured and indicated plus 92.4 Mt inferred resources. Next steps include US$13.2 million for drilling, metallurgical work, and water and tailings studies ahead of prefeasibility.
Watson-Marlow Fluid Technology Solutions has launched the Bredel QLINE low-pulsation peristaltic pump range for chemical dosing and fluid transfer, targeting smoother, higher flow rates than conventional hose pumps. The compact units are designed to improve dosing accuracy and cut pressure fluctuations, reducing mechanical stress on pipework, valves and inline instruments in mining reagent and slurry circuits. For plant engineers, lower pulsation should simplify control-loop tuning, extend hose and seal life, and reduce the need for pulsation dampeners on critical dosing lines.
Emerson is partnering with Databricks to provide native access to AspenTech Inmation™ OT Data Fabric from the Databricks Data + AI Platform, enabling mining operators to merge high-frequency plant control data with enterprise business datasets in a single environment. The integration is aimed at making historian, SCADA and sensor streams “AI-ready” for use in Databricks’ lakehouse architecture, supporting use cases such as predictive maintenance models and process optimisation. For mine operators, this reduces bespoke OT/IT integration work and should accelerate deployment of advanced analytics across dispersed sites.
MMD Group has signed a strategic cooperation framework agreement with China National Coal Development Co Ltd, a wholly owned subsidiary of China National Coal Group, during the 9th China International Import Expo in Shanghai. The deal, signed by MMD Managing Director Martin Vorster and CNCDC President Ben Zhang, formalises collaboration on mineral sizing and coal handling solutions in the Chinese market. For mine planners and process engineers, the partnership signals closer integration of MMD’s sizers and in-pit sizing technology with large-scale Chinese coal projects operated under the China National Coal Group umbrella.
LiuGong has unveiled an expanded electric mining line-up in Liuzhou, centred on the new DE100CE 100 t class battery haul truck showcased at its 2026 Global Distributor Annual Conference and Global Customer Festival. More than 2,000 delegates from over 120 countries saw multiple zero-emission machines positioned for construction and mining fleets, integrating battery-electric drivetrains with intelligent control systems. For mine operators, the scale of the 100 t truck signals growing OEM readiness for large-payload battery haulage in pit environments traditionally dominated by diesel.
Waratah Minerals has locked in $50 million in equity commitments to accelerate exploration at its Spur gold project in New South Wales, funding more than 100,000m of drilling over the next 12 months. The placement, backed by new and existing institutional investors, will support an intensive reverse circulation and diamond drilling programme targeting resource growth and higher-confidence classification. For geologists and mine planners, the scale of drilling signals a rapid tightening of geological models, with short lead times to update resource estimates and potential pit shell designs.
Gorilla Gold has raised $60 million in institutional funding via a two‑tranche placement at 26.5 cents per share to progress its proposed acquisition of IGO’s Cosmos nickel project in Western Australia and ramp up exploration across its gold portfolio. Tembo Capital, a resources‑focused investor, cornerstoned the deal with a $30 million commitment, with the remaining $30 million taken up by other institutional backers. The funding signals renewed development potential at Cosmos, with scope for near‑mine drilling, resource definition and restart studies in a tier‑one nickel province.
Forrestania Resources is preparing to restart gold production at the Edna May operation in Western Australia, targeting a December gold pour after locking in critical supply and mining services. A long-term sodium cyanide supply contract has been signed with Australian Gold Reagents, and Campbell Gold Haulage has been awarded the ore-loading and crusher-feed contract, securing run-of-mine handling to the primary crusher. With equipment and personnel mobilisation under way, processing continuity and reagent security are largely de-risked ahead of plant ramp-up.
Mineral Resources has appointed Perenti chief financial officer Michael Ellis as its next CFO, replacing long‑serving finance head Mark Wilson, who is retiring. Ellis, who joins MinRes on 19 May 2027, brings over 20 years’ finance experience, including more than a decade in mining services across contract mining, drilling and maintenance businesses. Executive general manager finance Jonathan Cowper will support the transition, signalling continuity in capital allocation, project financing and cost control across MinRes’ lithium, iron ore and mining services portfolio.
South Australia has awarded over $4.6 million in Plan for Accelerated Minerals (PACE) exploration grants to support up to 19 mineral projects, with the State Government expecting the funding to trigger more than $12 million in drilling and geophysics in 2027. The first-round grants target new copper, critical minerals and gold opportunities across multiple greenfield tenements, rather than brownfield resource extensions. Geologists and contractors can expect increased demand for deep RC and diamond drilling, high-resolution airborne surveys and basin-scale structural interpretation over the next 12–24 months.