Geomechanics.io

  • Free Tools
Sign UpLog In
Built byBoxcut Studio

Geomechanics.io

Geomechanics, Streamlined.

© 2026 Geomechanics.io. All rights reserved.

Geomechanics.io

CMRR-ioGEODB-ioHYDROGEO-ioQCDB-ioFree Tools & CalculatorsBlogLatest Industry News

Industries

MiningConstructionTunnelling

Company

Terms of UsePrivacy PolicyLinkedIn
    Projects

    Gold dominates 65% of Australia’s mining deals: project finance signals for engineers

    December 5, 2025|

    Reviewed by Joe Ashwell

    Gold dominates 65% of Australia’s mining deals: project finance signals for engineers

    First reported on Australian Mining Review – News

    30 Second Briefing

    Gold projects drove 65% of Australia’s FY25 mining deals, with $12.6b of $18.7b in transactions and a 94% surge in gold sector market capitalisation to $64.8b as prices passed $5,341/oz, while overall mid-tier market cap rose 15% to $128.6b. Critical minerals lagged, with market capitalisation down 20% to $37.1b and operating cash flow falling 71% to $0.9b, despite the $13b US–Australia agreement and new tax credits. Of 900 identified critical mineral projects, 124 are “investment-ready” but stalled pre‑FID, most with NPVs clustered around $600m and weak NPV-to-capex ratios, leaving a financing and offtake gap that foreign partners from the US, Japan and Korea are now targeting.

    Technical Brief

    • PwC’s Aussie Mine Report 2025 analysed 50 Australian mid-tier miners to quantify deal and capital flows.
    • Gold-related mining deals in FY25 increased 216% year-on-year in value terms.
    • Only seven new “investable” critical minerals projects were added to the pipeline over the past year.
    • Of 900 identified critical mineral projects, 124 are classed as “investment-ready” but remain pre‑FID.
    • Around one quarter of these 124 projects report proven and probable reserves, limiting bankability.
    • Few investment-ready projects disclose NPVs above $1b; many cluster near $600m with NPV:capex <2.
    • Long-term, patient capital is reported as scarce for funding definitive feasibility studies and early development.
    • Federal physical stockpiles and price support schemes are intended to de-risk price/volume for critical minerals.
    • Many projects lack offtake agreements or finance approvals, creating a pronounced “valley” between discovery and production.
    • Strategic partners from the US, Japan and Korea are actively targeting Australian critical minerals for defence and energy supply chains.

    Our Take

    The 94% rise in Australian gold sector market capitalisation alongside record gold prices echoes the World Gold Council’s 2026 outlook in our coverage, which highlights sustained central bank demand as a structural support for gold-focused deal-making.

    The 20% fall in critical minerals market capitalisation and 71% drop in operating cash flow sit uncomfortably against the US–Australia critical minerals agreement value of $13b, suggesting policy support is not yet translating into robust project economics for many of the 900 identified projects.

    With many critical mineral projects clustering around an NPV of about $600m and few exceeding a 2:1 NPV-to-capex ratio, Australian proponents may need to lean more heavily on downstream partnerships with Japan and Korea to de-risk financing compared with gold projects that are currently attracting most domestic deal flow.

    Geotechnical Software for Modern Teams

    Centralise site data, logs, and lab results with GEODB-io, CMRR-io, and HYDROGEO-io.

    No credit card required.

    • Save and export unlimited calculations
    • Advanced data visualisation
    • Generate professional PDF reports
    • Cloud storage for all your projects

    Prepared by collating external sources, AI-assisted tools, and Geomechanics.io’s proprietary mining database, then reviewed for technical accuracy & edited by our geotechnical team.

    Related Articles

    McEwen’s $55M Ontario asset sale: production growth lens for mine planners
    Mining
    about 20 hours ago

    McEwen’s $55M Ontario asset sale: production growth lens for mine planners

    McEwen has agreed to sell its Fuller and Paymaster gold properties in Ontario’s Timmins district to Discovery Mining for $55 million in cash and stock, freeing capital to push a production target of 250,000–300,000 gold-equivalent ounces per year by 2030. The deal covers 210 hectares at Fuller, a 60% stake in the 179-hectare Paymaster property, and associated surface rights, consolidating Paymaster under Discovery’s Dome Mine subsidiary. Proceeds will be reinvested into the Fox Complex (Froome, Stock, Grey Fox), Nevada’s Gold Bar Complex, and Mexico’s El Gallo build, with Stock Mine slated for first ore in Q4 2026 and commercial output in Q1 2027.

    Lithium Triangle extraction hurdles: hydrogeological insights for project teams
    Mining
    about 20 hours ago

    Lithium Triangle extraction hurdles: hydrogeological insights for project teams

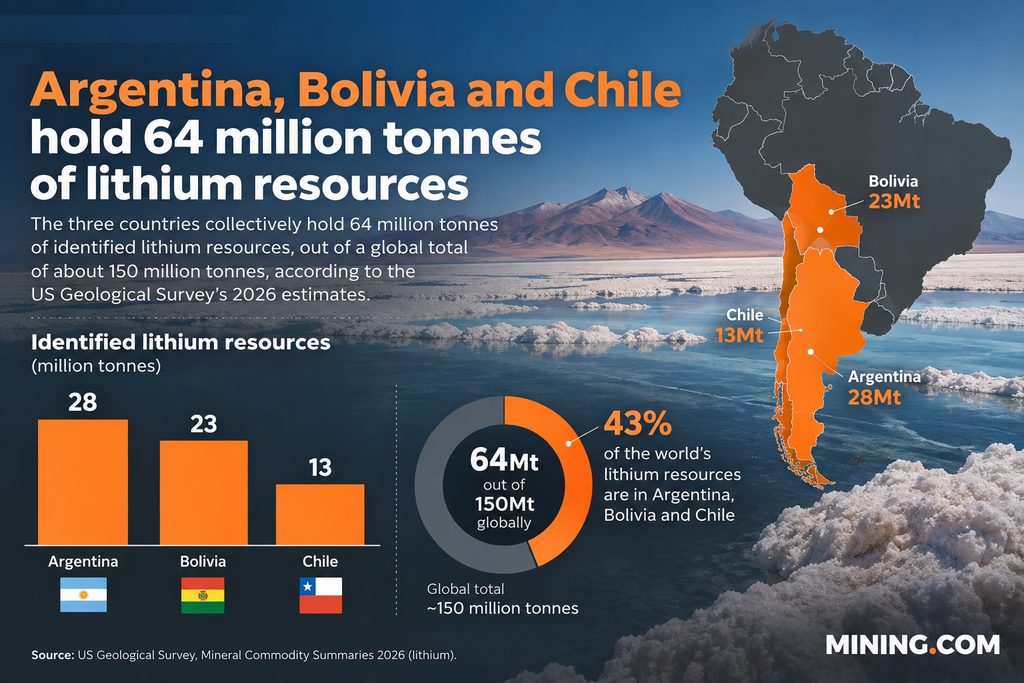
    South America’s Lithium Triangle holds about 64 million tonnes of identified lithium resources (43% of the global 150 million tonnes), yet geologist José Cabello’s review of 43 salt flats across Argentina, Bolivia and Chile shows that variable brine chemistry, impurities and groundwater behaviour make recovery and costs highly site-specific. Salar de Atacama benefits from ultra‑dry climate, relatively clean brines and strong logistics, while other basins such as Altoandinos, Pedernales, Hombre Muerto Oeste, Rincón, Sal de los Ángeles and Sal de Vida face tighter water and hydrogeological constraints. Direct lithium extraction (DLE) could unlock lower‑grade or impurity‑rich brines, but Cabello stresses that trade‑offs between brine withdrawal and freshwater consumption mean technology selection must be tailored to each basin’s hydrology and ecosystem.

    KGHM’s $2.4bn copper projects fast-tracked: CRMA implications for mine planners
    Mining
    about 20 hours ago

    KGHM’s $2.4bn copper projects fast-tracked: CRMA implications for mine planners

    EU regulators have granted strategic status under the Critical Raw Materials Act to KGHM’s 9.5‑billion‑zloty ($2.44bn) Retków‑Grodziszcze mine and Legnica smelter conversion, unlocking faster permitting, streamlined administration and access to preferential financing. Retków‑Grodziszcze is planned to deliver over 100 million tonnes of ore by 2055, yielding about 1.5 million tonnes of copper and 5,000 tonnes of silver, while Legnica’s recycling line targets 135,000 tonnes of electrolytic copper and 250 tonnes of nickel per year. The move materially boosts EU copper and nickel recycling capacity, central to the CRMA’s 25% recycling target.

    Related Industries & Products

    Mining

    Geotechnical software solutions for mining operations including CMRR analysis, hydrogeological testing, and data management.

    CMRR-io

    Streamline coal mine roof stability assessments with our cloud-based CMRR software featuring automated calculations, multi-scenario analysis, and collaborative workflows.

    HYDROGEO-io

    Comprehensive hydrogeological testing platform for managing, analysing, and reporting on packer tests, lugeon values, and hydraulic conductivity assessments.

    GEODB-io

    Centralised geotechnical data management solution for storing, accessing, and analysing all your site investigation and material testing data.

    AllGeotechnicalInfrastructureHazardsEnvironmental