Geomechanics.io

  • Free Tools
Sign UpLog In
Built byBoxcut Studio

Geomechanics.io

Geomechanics, Streamlined.

© 2026 Geomechanics.io. All rights reserved.

Geomechanics.io

CMRR-ioGEODB-ioHYDROGEO-ioQCDB-ioFree Tools & CalculatorsBlogLatest Industry News

Industries

MiningConstructionTunnelling

Company

Terms of UsePrivacy PolicyLinkedIn
    Projects
    Research
    Sustainability

    Global mining as a brownfield industry: risk and capex insights for project teams

    January 23, 2026|

    Reviewed by Joe Ashwell

    Global mining as a brownfield industry: risk and capex insights for project teams

    First reported on MINING.com

    30 Second Briefing

    Global mine development has shifted decisively to brownfield expansion, with a University of Queensland study of 366 sites in 58 countries showing brownfield capital dominated by copper (just under 50%), followed by gold (17.5%), iron ore (14.4%) and nickel (6.3%). Chile accounts for 25.2% of global brownfield capex, ahead of the US (11.4%) and Australia (10.1%), while minesite exploration by majors in Pacific and Southeast Asia has surged from 27.3% of budgets in 2010 to 76.8% in 2024. Nearly 80% of brownfield mines assessed via satellite sit in areas with multiple high-risk conditions, and over half lie within 20 km of biodiversity hotspots or protected areas, signalling tighter geotechnical, water and permitting constraints for future expansions.

    Technical Brief

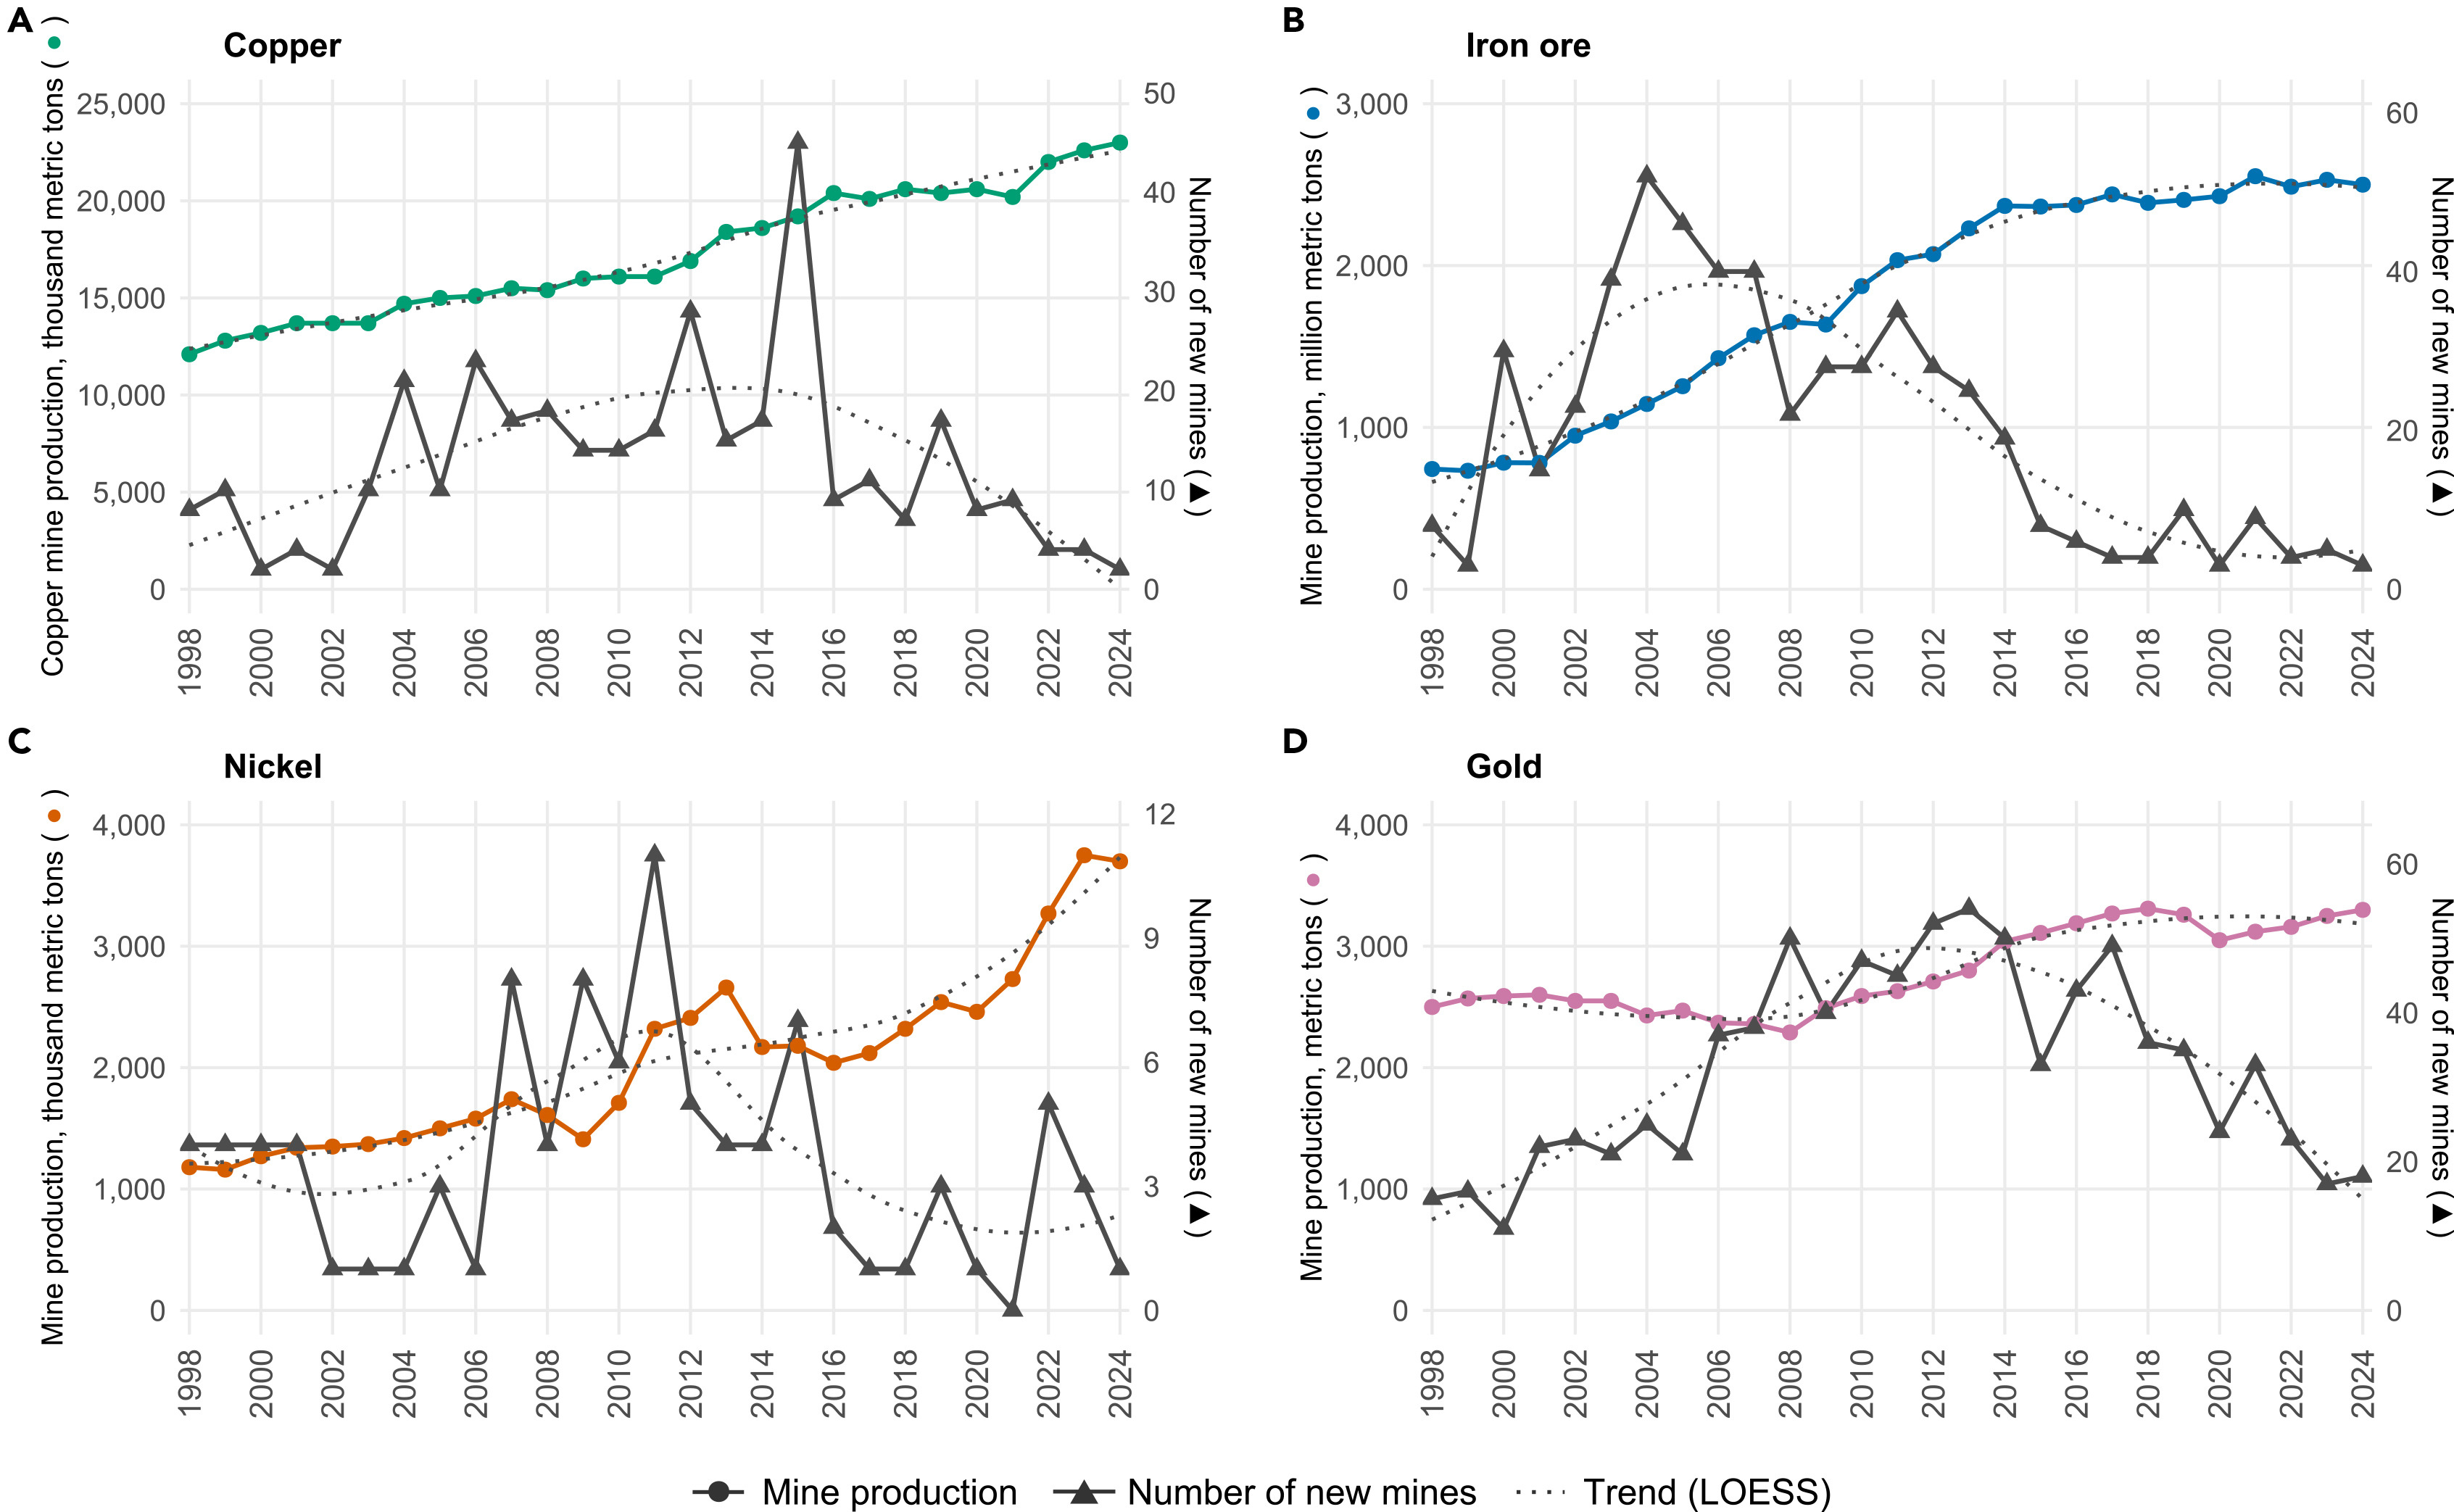
    • Study covers 366 brownfield mine sites across 58 countries and 16 mineral commodities (1998–2024).
    • Researchers combined global production, exploration and capex datasets, smoothing time-series trends using LOESS regression.
    • New copper mines peaked around 2015, while iron ore, nickel and gold peaks occurred between early 2000s–2014.
    • Brownfield growth is described as incremental, with stepwise regulatory approvals but cumulative social and environmental risk escalation.

    Our Take

    With copper accounting for just under half of brownfield capex in the study and a 14+4 year path from discovery to production, operators in regions like Latin America and Africa are likely to lean harder on incremental expansions at existing copper assets rather than betting on greenfield timelines that miss the 2030s demand window.

    The sharp rise in minesite exploration shares in Pacific/Southeast Asia and Africa between 2010 and 2024 signals that brownfield optionality for critical minerals such as cobalt, nickel and copper is increasingly concentrated in jurisdictions where permitting, water stress and governance risks are already prominent in our sustainability-tagged coverage.

    With nearly 80% of brownfield mines in multiple high-risk locations and over half within 20 km of biodiversity hotspots, ESG-screened capital for projects like Arizona Sonoran Copper’s Cactus brownfield development will likely hinge on demonstrating that expansions reduce the overall disturbance footprint versus equivalent greenfield capacity.

    Geotechnical Software for Modern Teams

    Centralise site data, logs, and lab results with GEODB-io, CMRR-io, and HYDROGEO-io.

    No credit card required.

    • Save and export unlimited calculations
    • Advanced data visualisation
    • Generate professional PDF reports
    • Cloud storage for all your projects

    Prepared by collating external sources, AI-assisted tools, and Geomechanics.io’s proprietary mining database, then reviewed for technical accuracy & edited by our geotechnical team.

    Related Articles
    Vulcan Elements–North Carolina rare earth magnets: design and supply notes for engineers
    Mining
    about 7 hours ago

    Vulcan Elements–North Carolina rare earth magnets: design and supply notes for engineers

    Vulcan Elements has partnered with the North Carolina Collaboratory and UNC-Chapel Hill chemist Yosuke Kanai to use quantum-mechanical simulations to predict how atomic-level changes affect rare earth magnet properties, backed by a $600,000 research award. The work feeds directly into Vulcan’s 1.1 million-square-foot Benson, North Carolina plant, designed for 10,000 t/y of magnet production and billed as the largest rare earth magnet factory outside China. Vulcan claims its material, technology, software, IP and ownership are fully decoupled from Chinese supply chains, aligning with its existing $1.4 billion US government-backed partnership with ReElement Technologies.

    Northern Star KCGM expansion: commissioning timeline and capacity cues for engineers
    Mining
    about 7 hours ago

    Northern Star KCGM expansion: commissioning timeline and capacity cues for engineers

    Northern Star Resources has completed the tie-in of its expanded KCGM processing plant in Western Australia, with commissioning of the integrated circuit now under way ahead of a planned production ramp-up in the second half of FY27. Early commissioning is focused on achieving stable, sustained operating conditions across the enlarged plant, rather than immediate throughput gains. For plant and process engineers, the timeline signals when additional milling, crushing and gold recovery capacity at KCGM is expected to start contributing materially to output and unit cost performance.

    Regis Resources and McPhillamys: funding optionality and schedule signals for engineers
    Mining
    about 7 hours ago

    Regis Resources and McPhillamys: funding optionality and schedule signals for engineers

    Regis Resources ended the September quarter with $1.28 billion in cash and bullion after generating $265 million in operating cash flow and collecting a $51 million break fee from Vault Minerals, following its decision not to match Genesis Minerals’ competing offer. The strengthened balance sheet gives Regis substantial optionality on funding the McPhillamys gold project in New South Wales, rather than relying heavily on project finance or equity. For mine planners and project engineers, this signals potential acceleration of McPhillamys approvals, early works and long-lead procurement once a final investment decision is made.

    Related Industries & Products

    Mining

    Geotechnical software solutions for mining operations including CMRR analysis, hydrogeological testing, and data management.

    CMRR-io

    Streamline coal mine roof stability assessments with our cloud-based CMRR software featuring automated calculations, multi-scenario analysis, and collaborative workflows.

    HYDROGEO-io

    Comprehensive hydrogeological testing platform for managing, analysing, and reporting on packer tests, lugeon values, and hydraulic conductivity assessments.

    GEODB-io

    Centralised geotechnical data management solution for storing, accessing, and analysing all your site investigation and material testing data.

    AllGeotechnicalInfrastructureHazardsEnvironmental