Geomechanics.io

  • Free Tools
Sign UpLog In
Built byBoxcut Studio

Geomechanics.io

Geomechanics, Streamlined.

© 2026 Geomechanics.io. All rights reserved.

Geomechanics.io

CMRR-ioGEODB-ioHYDROGEO-ioQCDB-ioFree Tools & CalculatorsBlogLatest Industry News

Industries

MiningConstructionTunnelling

Company

Terms of UsePrivacy PolicyLinkedIn
    Projects

    USGS China chokehold warning: supply risk and project signals for US miners

    February 7, 2026|

    Reviewed by Joe Ashwell

    USGS China chokehold warning: supply risk and project signals for US miners

    First reported on MINING.com

    30 Second Briefing

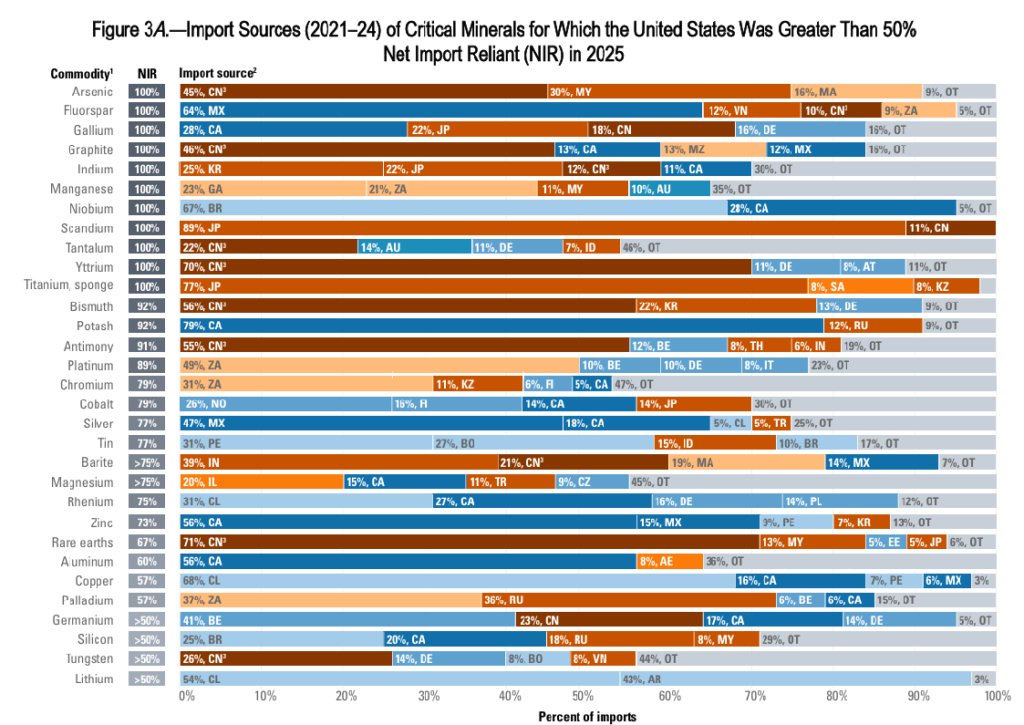
    US mineral supply chains became more exposed in 2025, with the USGS reporting 100% import reliance for 16 of 90 tracked non-fuel commodities and more than 50% reliance for 54 minerals, up from 15 and 46 respectively in 2024. The US is totally dependent on imports of arsenic, natural graphite, manganese, niobium, tantalum, titanium sponge and 10 other minerals, with China supplying nearly half of arsenic and graphite, 55% of antimony and 70% of rare earths. In response, the Trump administration has proposed a $12 billion critical minerals stockpile and a JD Vance-led allied trade bloc, while industry warns US mine permitting still averages 29 years.

    Technical Brief

    • USGS 2026 Mineral Commodities Summary covers 90 non-fuel mineral commodities in its dependency analysis.
    • Sixteen fully import-dependent commodities include arsenic, asbestos, cesium, fluorspar, gallium, natural graphite and indium.
    • Additional fully import-reliant minerals are manganese, natural mica, niobium (columbium), rubidium, scandium, strontium, tantalum, titanium sponge and yttrium.
    • Only three of those 16 (asbestos, mica, strontium) are absent from the formal USGS critical minerals list.
    • A further 20 critical minerals show net import reliance above 50%, down from 28 the previous year.
    • China supplies about 55% of US antimony imports and roughly 70% of rare earth elements.
    • Canada is the leading import source for US aluminium, gallium, potash and zinc supply chains.
    • Chile and Mexico dominate US import sourcing for newly listed criticals copper and silver, respectively.
    • National Mining Association cites an average 29-year timeline from discovery to production for US mines, constraining rapid reshoring.

    Our Take

    The planned $12 billion US critical minerals stockpile flagged in the separate “Project Vault” policy piece in our coverage directly echoes the USGS concern here, signalling that materials like gallium, graphite and rare earths are being treated as strategic assets rather than just industrial inputs.

    In our database, USGS appears not only as a data provider in this report but also as a reference point in silver and copper market analysis, which suggests its critical minerals tracking is increasingly being used by investors as much as by policymakers.

    The 29‑year average mine development time in the US means that, for many of the 20–28 critical minerals with >50% net import reliance, near‑term supply security will likely depend more on stockpiling and offtake from allies such as Canada, Chile and Mexico than on new domestic greenfield projects.

    Geotechnical Software for Modern Teams

    Centralise site data, logs, and lab results with GEODB-io, CMRR-io, and HYDROGEO-io.

    No credit card required.

    • Save and export unlimited calculations
    • Advanced data visualisation
    • Generate professional PDF reports
    • Cloud storage for all your projects

    Prepared by collating external sources, AI-assisted tools, and Geomechanics.io’s proprietary mining database, then reviewed for technical accuracy & edited by our geotechnical team.

    Related Articles

    Brazil survey plan: access, data priority and licence risks for mine planners
    Policy
    about 16 hours ago

    Brazil survey plan: access, data priority and licence risks for mine planners

    Brazil’s Geological Survey (SGB) is advancing a 10‑year, 3.3‑billion‑real airborne geophysical survey plan that could grant co‑funders such as Petrobras and Vale temporary exclusive access to magnetics and conductivity data before it becomes public. Because Brazil’s Mining Code awards exploration rights to the first qualifying applicant, early access to regional datasets could let major backers secure prime copper, gold, iron ore, lithium and rare earths ground ahead of juniors. Industry groups including ABPM are pushing for strict safeguards, seeking exclusivity capped at six months, limited to co‑funded areas and with no mineral rights priority attached.

    Greenland seabed mining ban to 2029: project siting implications for engineers
    Policy
    4 days ago

    Greenland seabed mining ban to 2029: project siting implications for engineers

    Greenland’s parliament has unanimously backed a resolution to ban seabed mineral extraction until at least the end of 2029, with possible two‑year extensions, directly countering US plans for “massive oil, gas and mineral exploration” announced by President Trump. The ban will cover prospective deep-sea mining of polymetallic nodules and other seabed resources, even as the US moves towards permitting such operations in international waters. For miners eyeing Greenland’s 28.2 Mt TREO Tanbreez rare earth project and wider critical mineral endowment, the decision sharply narrows options to land-based developments.

    Canada’s new foreign investment rules: financing impacts for critical minerals projects
    Policy
    4 days ago

    Canada’s new foreign investment rules: financing impacts for critical minerals projects

    Canada’s 2024 Investment Canada Act amendments will, from early 2027, impose mandatory pre-closing filings on certain non-control foreign investments in “prescribed” sensitive sectors, expected to include critical minerals, where investors gain access to material non-public technical information, key assets or governance rights. Critical minerals juniors relying on strategic minority investors for exploration, feasibility and project build-out may face at least a 45-day national security screening, with some reviews extending to 200 days, forcing longer financing timelines and more complex deal structuring, such as staged tranches. Ottawa’s aim is to vet sensitive deals before closing and avoid repeat divestiture orders like the 2022 forced exits of Sinomine, Chengze Lithium and Zangge Mining from Canadian lithium and rare metals projects.

    Related Industries & Products

    Mining

    Geotechnical software solutions for mining operations including CMRR analysis, hydrogeological testing, and data management.

    CMRR-io

    Streamline coal mine roof stability assessments with our cloud-based CMRR software featuring automated calculations, multi-scenario analysis, and collaborative workflows.

    HYDROGEO-io

    Comprehensive hydrogeological testing platform for managing, analysing, and reporting on packer tests, lugeon values, and hydraulic conductivity assessments.

    GEODB-io

    Centralised geotechnical data management solution for storing, accessing, and analysing all your site investigation and material testing data.

    AllGeotechnicalInfrastructureHazardsEnvironmental