Geomechanics.io

  • Free Tools
Sign UpLog In
Built byBoxcut Studio

Geomechanics.io

Geomechanics, Streamlined.

© 2026 Geomechanics.io. All rights reserved.

Geomechanics.io

CMRR-ioGEODB-ioHYDROGEO-ioQCDB-ioFree Tools & CalculatorsBlogLatest Industry News

Industries

MiningConstructionTunnelling

Company

Terms of UsePrivacy PolicyLinkedIn
    Projects
    Contract Award

    USA Rare Earth $2.8B Serra Verde deal: supply, capex and mine plan notes for engineers

    April 21, 2026|

    Reviewed by Joe Ashwell

    USA Rare Earth $2.8B Serra Verde deal: supply, capex and mine plan notes for engineers

    First reported on MINING.com

    30 Second Briefing

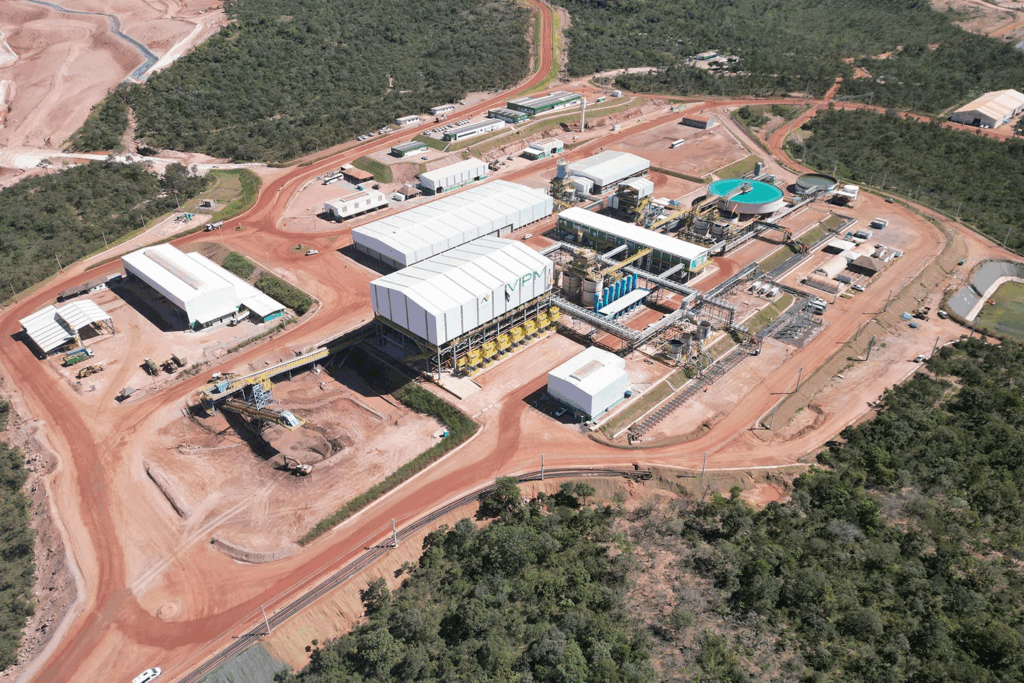
    USA Rare Earth will acquire Brazil’s Serra Verde Group for about US$2.8 billion in cash and shares, securing the Pela Ema ionic clay rare earths mine in Goiás, Latin America’s only producing rare earths operation and a key source of heavy Dy, Tb and Y. The deal includes a 15-year offtake for Nd, Pr, Dy and Tb to a US-backed special purpose entity and links Brazilian feedstock with USA Rare Earth’s planned magnet plant in Stillwater, Oklahoma and its Round Top project in Texas. Serra Verde’s stage one nameplate capacity is 6,400 t/y TREO, targeting over 50% of heavy rare earth output outside China by 2027 and projected EBITDA of US$550–650 million by end-2027.

    Technical Brief

    • Deal consideration comprises US$300 million cash plus 126.849 million new USA Rare Earth shares at US$19.95.
    • Pela Ema’s ionic clay mineralisation is soft, near-surface and mined without drilling or blasting.
    • Stage one plant is designed for 6,400 t/y TREO nameplate, with a planned stage two expansion.
    • Mine life is estimated at 25 years, with targeted EBITDA of US$550–650 million by end-2027.
    • Serra Verde closed a US$565 million DFC funding package for Pela Ema operational upgrades in early 2026.
    • USA Rare Earth’s Round Top project in Texas is scheduled for first production in late 2028.
    • A 15‑year offtake to a US‑backed special purpose entity includes minimum floor prices for Nd, Pr, Dy, Tb.

    Our Take

    In our database, USA Rare Earth’s commissioning of NdFeB magnet production in Stillwater, Oklahoma and its first commercial yttrium metal output in the UK indicate that acquiring Serra Verde in Goiás gives it upstream heavy rare earth feed to back an already emerging mine-to-magnet chain across three continents.

    The International Development Finance Corporation’s prior US$465 million plus US$100 million top-up for Serra Verde, alongside Washington’s separate commitment of up to US$1.6 billion for USA Rare Earth’s Round Top project in Texas, signals that this Brazil M&A deal is effectively knitting together two DFC-backed critical mineral pillars in the Americas.

    With Serra Verde projected to supply about half of non-Chinese heavy rare earth output by 2027 and Lynas Rare Earths reporting A$265 million in quarterly revenue from a more diversified base, this transaction positions USA Rare Earth as a direct competitive counterweight to Lynas and MP Materials in future dysprosium–terbium and NdPr offtake negotiations.

    Geotechnical Software for Modern Teams

    Centralise site data, logs, and lab results with GEODB-io, CMRR-io, and HYDROGEO-io.

    No credit card required.

    • Save and export unlimited calculations
    • Advanced data visualisation
    • Generate professional PDF reports
    • Cloud storage for all your projects

    Prepared by collating external sources, AI-assisted tools, and Geomechanics.io’s proprietary mining database, then reviewed for technical accuracy & edited by our geotechnical team.

    Related Articles

    Minnova’s C$76M PL gold mine restart: economics and strip risks for engineers
    Mining
    about 11 hours ago

    Minnova’s C$76M PL gold mine restart: economics and strip risks for engineers

    Minnova plans a C$76.2 million restart of the brownfield PL gold mine near Sherridon, Manitoba, targeting 62,200 oz per year over 10 years from a high‑grade open pit feeding an existing 1,000 t/d plant, which is slated to double to 2,000 t/d in year two. The September resource stands at 3.76 million measured and indicated tonnes at 4.98 g/t Au (601,158 oz) plus 1.67 million inferred tonnes at 3.78 g/t (202,810 oz), with open pits carrying a high 21:1 waste‑to‑ore strip ratio. At US$3,000/oz gold, the PEA projects an after‑tax NPV5 of US$180.6 million, 111% IRR, eight‑month payback and all‑in sustaining costs of US$2,288/oz, but value falls sharply at lower prices, underlining cost and strip sensitivity.

    Mining
    about 11 hours ago

    Caterpillar Resource Industries leadership shift: fleet and autonomy cues for miners

    Caterpillar has confirmed that Denise Johnson, Group President of Resource Industries since 2016 and a key figure in expanding autonomous haulage and large mining truck platforms, will retire on 1 February 2027. Derrick York, currently President of Solar Turbines and a Caterpillar Senior Vice President overseeing industrial gas turbines and compressor sets, will become Group President of Resource Industries on 1 November 2026, with Johnson shifting to an advisory role. The handover timetable gives miners nearly a year of overlap to align major fleet, autonomy and support contracts with the incoming leadership.

    Anglo American copper scarcity and tech tie-ups: key takeaways for mine planners
    Mining
    about 11 hours ago

    Anglo American copper scarcity and tech tie-ups: key takeaways for mine planners

    Tech companies are in talks to buy equity in Anglo American to secure long-term copper and other data centre metals, as Comex copper trades near $6.52/lb and LME cash copper recently hit a record $14,822/t. Anglo’s planned merger with Teck Resources would create a roughly $90 billion group producing about 1.2 million tonnes of copper per year, controlling around 5% of global supply, but is still awaiting Chinese antitrust clearance tied to concentrate flows to local smelters. Wanblad also warned Anglo may close its Brazilian nickel operations at Codemin and Barro Alto if the EU blocks the $500 million sale to MMG despite proposed long-term European ferronickel supply commitments.

    Related Industries & Products

    Mining

    Geotechnical software solutions for mining operations including CMRR analysis, hydrogeological testing, and data management.

    CMRR-io

    Streamline coal mine roof stability assessments with our cloud-based CMRR software featuring automated calculations, multi-scenario analysis, and collaborative workflows.

    HYDROGEO-io

    Comprehensive hydrogeological testing platform for managing, analysing, and reporting on packer tests, lugeon values, and hydraulic conductivity assessments.

    GEODB-io

    Centralised geotechnical data management solution for storing, accessing, and analysing all your site investigation and material testing data.

    AllGeotechnicalInfrastructureHazardsEnvironmental