Geomechanics.io

  • Free Tools
Sign UpLog In
Built byBoxcut Studio

Geomechanics.io

Geomechanics, Streamlined.

© 2026 Geomechanics.io. All rights reserved.

Geomechanics.io

CMRR-ioGEODB-ioHYDROGEO-ioQCDB-ioFree Tools & CalculatorsBlogLatest Industry News

Industries

MiningConstructionTunnelling

Company

Terms of UsePrivacy PolicyLinkedIn
    Projects
    Op-Ed
    Sustainability

    Tungsten and critical minerals: investment shift and CDOI lens for project teams

    July 8, 2026|

    Reviewed by Tom Sullivan

    Tungsten and critical minerals: investment shift and CDOI lens for project teams

    First reported on MINING.com

    30 Second Briefing

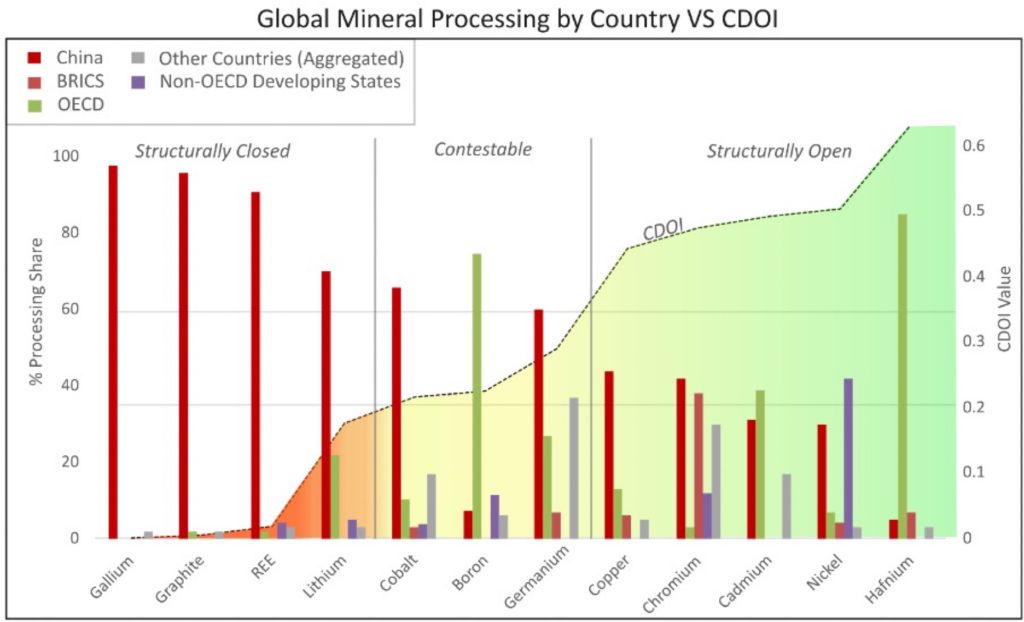
    China’s structurally closed midstream processing dominance in gallium, graphite, rare earths, lithium and tungsten is described as effectively impossible to dislodge, prompting Nicholas Vafeas to propose a “Critical Dominance Opportunity Index” (CDOI) to measure where new entrants can still gain leverage. Base metals such as copper, nickel and chromium remain contestable, whereas tungsten shows how China is now moving to monopolise circularity frameworks and secondary processing of tungsten waste streams. The argument is that Western €10 billion-scale investments must shift from “catch-up” refining in closed markets to contestable midstream and recycling niches where strategic control is still achievable.

    Technical Brief

    • Structurally closed midstream markets are defined as those where new capacity cannot rationally displace incumbent ecosystem advantages.
    • Ecosystem dominance is framed as thousands of incremental logistics, know‑how and supplier advantages, not just plant capacity share.
    • Loss of coordination in these OECD‑dominated niches is identified as a specific backdoor for rapid hostile consolidation.
    • Tungsten is used as a worked example where industrial waste and secondary streams become the next strategic battleground.
    • China’s tungsten strategy is described as extending existing midstream control into recycling and circularity standards, not changing course.
    • Policy distinction is drawn between capital for resilience (domestic redundancy, stockpiles) versus capital for future dominance (contestable midstream).

    Our Take

    Coverage tied to Australia, Canada and the USA in our Mining stories increasingly links critical raw materials to permitting and ESG constraints, which suggests that securing domestic supply of tungsten, gallium and hafnium will likely hinge as much on social licence and processing footprints as on ore discovery.

    China appears frequently across our critical raw materials coverage as a dominant processor of graphite, rare earth elements and gallium, implying that any investment ‘paradigm shift’ discussed here will probably revolve around de-risking that midstream dependence rather than just opening new mines in Latin America or Europe.

    Geotechnical Software for Modern Teams

    Centralise site data, logs, and lab results with GEODB-io, CMRR-io, and HYDROGEO-io.

    No credit card required.

    • Save and export unlimited calculations
    • Advanced data visualisation
    • Generate professional PDF reports
    • Cloud storage for all your projects

    Prepared by collating external sources, AI-assisted tools, and Geomechanics.io’s proprietary mining database, then reviewed for technical accuracy & edited by our geotechnical team.

    Related Articles
    Geopolitical risk and private capital flows: gold price signals for mine planners
    Mining
    about 12 hours ago

    Geopolitical risk and private capital flows: gold price signals for mine planners

    Growing geopolitical tensions are pushing capital out of sovereign bonds and into private assets, a rotation market-cycle analyst Martin Armstrong links to a potential renewed gold rally from Q1 next year. Armstrong sees Europe as particularly exposed, arguing EU states face rising war-related borrowing costs and inflation as “war drums” lift long-term rates, while bond markets “give us the real story”. He warns that if gold closes below $4,000/oz weekly it could test $3,500–$3,700, but expects elections in the US, Israel and Ukraine to keep geopolitical risk elevated and ultimately drive prices higher.

    McEwen’s $55M Ontario asset sale: production growth lens for mine planners
    Mining
    2 days ago

    McEwen’s $55M Ontario asset sale: production growth lens for mine planners

    McEwen has agreed to sell its Fuller and Paymaster gold properties in Ontario’s Timmins district to Discovery Mining for $55 million in cash and stock, freeing capital to push a production target of 250,000–300,000 gold-equivalent ounces per year by 2030. The deal covers 210 hectares at Fuller, a 60% stake in the 179-hectare Paymaster property, and associated surface rights, consolidating Paymaster under Discovery’s Dome Mine subsidiary. Proceeds will be reinvested into the Fox Complex (Froome, Stock, Grey Fox), Nevada’s Gold Bar Complex, and Mexico’s El Gallo build, with Stock Mine slated for first ore in Q4 2026 and commercial output in Q1 2027.

    Lithium Triangle extraction hurdles: hydrogeological insights for project teams
    Mining
    2 days ago

    Lithium Triangle extraction hurdles: hydrogeological insights for project teams

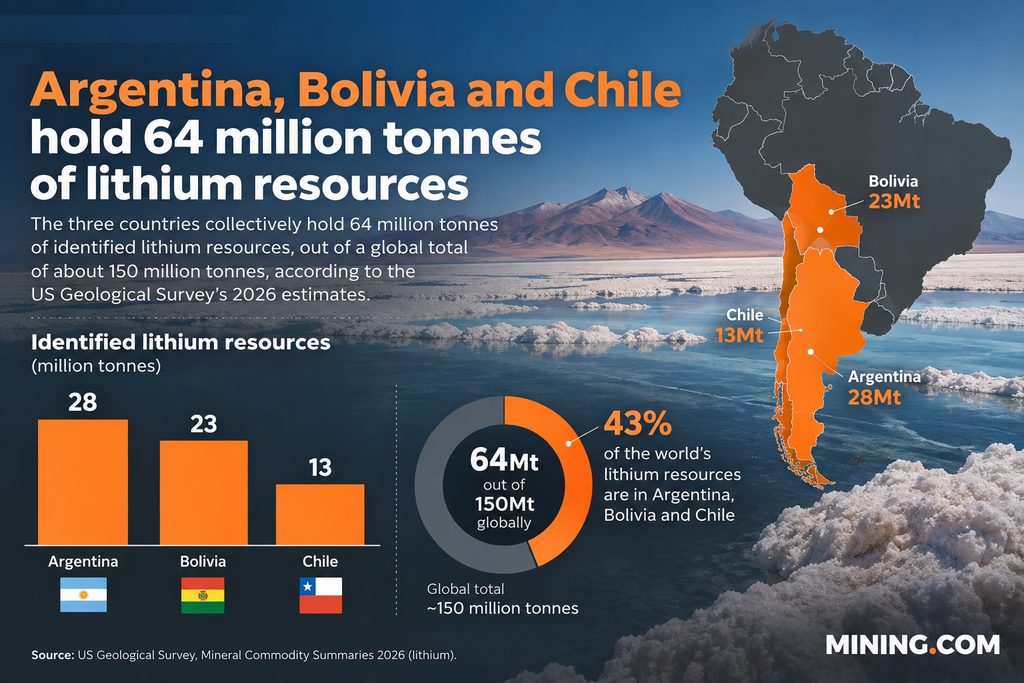
    South America’s Lithium Triangle holds about 64 million tonnes of identified lithium resources (43% of the global 150 million tonnes), yet geologist José Cabello’s review of 43 salt flats across Argentina, Bolivia and Chile shows that variable brine chemistry, impurities and groundwater behaviour make recovery and costs highly site-specific. Salar de Atacama benefits from ultra‑dry climate, relatively clean brines and strong logistics, while other basins such as Altoandinos, Pedernales, Hombre Muerto Oeste, Rincón, Sal de los Ángeles and Sal de Vida face tighter water and hydrogeological constraints. Direct lithium extraction (DLE) could unlock lower‑grade or impurity‑rich brines, but Cabello stresses that trade‑offs between brine withdrawal and freshwater consumption mean technology selection must be tailored to each basin’s hydrology and ecosystem.

    Related Industries & Products

    Mining

    Geotechnical software solutions for mining operations including CMRR analysis, hydrogeological testing, and data management.

    CMRR-io

    Streamline coal mine roof stability assessments with our cloud-based CMRR software featuring automated calculations, multi-scenario analysis, and collaborative workflows.

    HYDROGEO-io

    Comprehensive hydrogeological testing platform for managing, analysing, and reporting on packer tests, lugeon values, and hydraulic conductivity assessments.

    GEODB-io

    Centralised geotechnical data management solution for storing, accessing, and analysing all your site investigation and material testing data.

    AllGeotechnicalInfrastructureHazardsEnvironmental