Geomechanics.io

  • Free Tools
Sign UpLog In
Built byBoxcut Studio

Geomechanics.io

Geomechanics, Streamlined.

© 2026 Geomechanics.io. All rights reserved.

Geomechanics.io

CMRR-ioGEODB-ioHYDROGEO-ioQCDB-ioFree Tools & CalculatorsBlogLatest Industry News

Industries

MiningConstructionTunnelling

Company

Terms of UsePrivacy PolicyLinkedIn
    Projects

    EV battery metals index at 27‑month high: pricing and supply notes for miners

    February 17, 2026|

    Reviewed by Joe Ashwell

    EV battery metals index at 27‑month high: pricing and supply notes for miners

    First reported on MINING.com

    30 Second Briefing

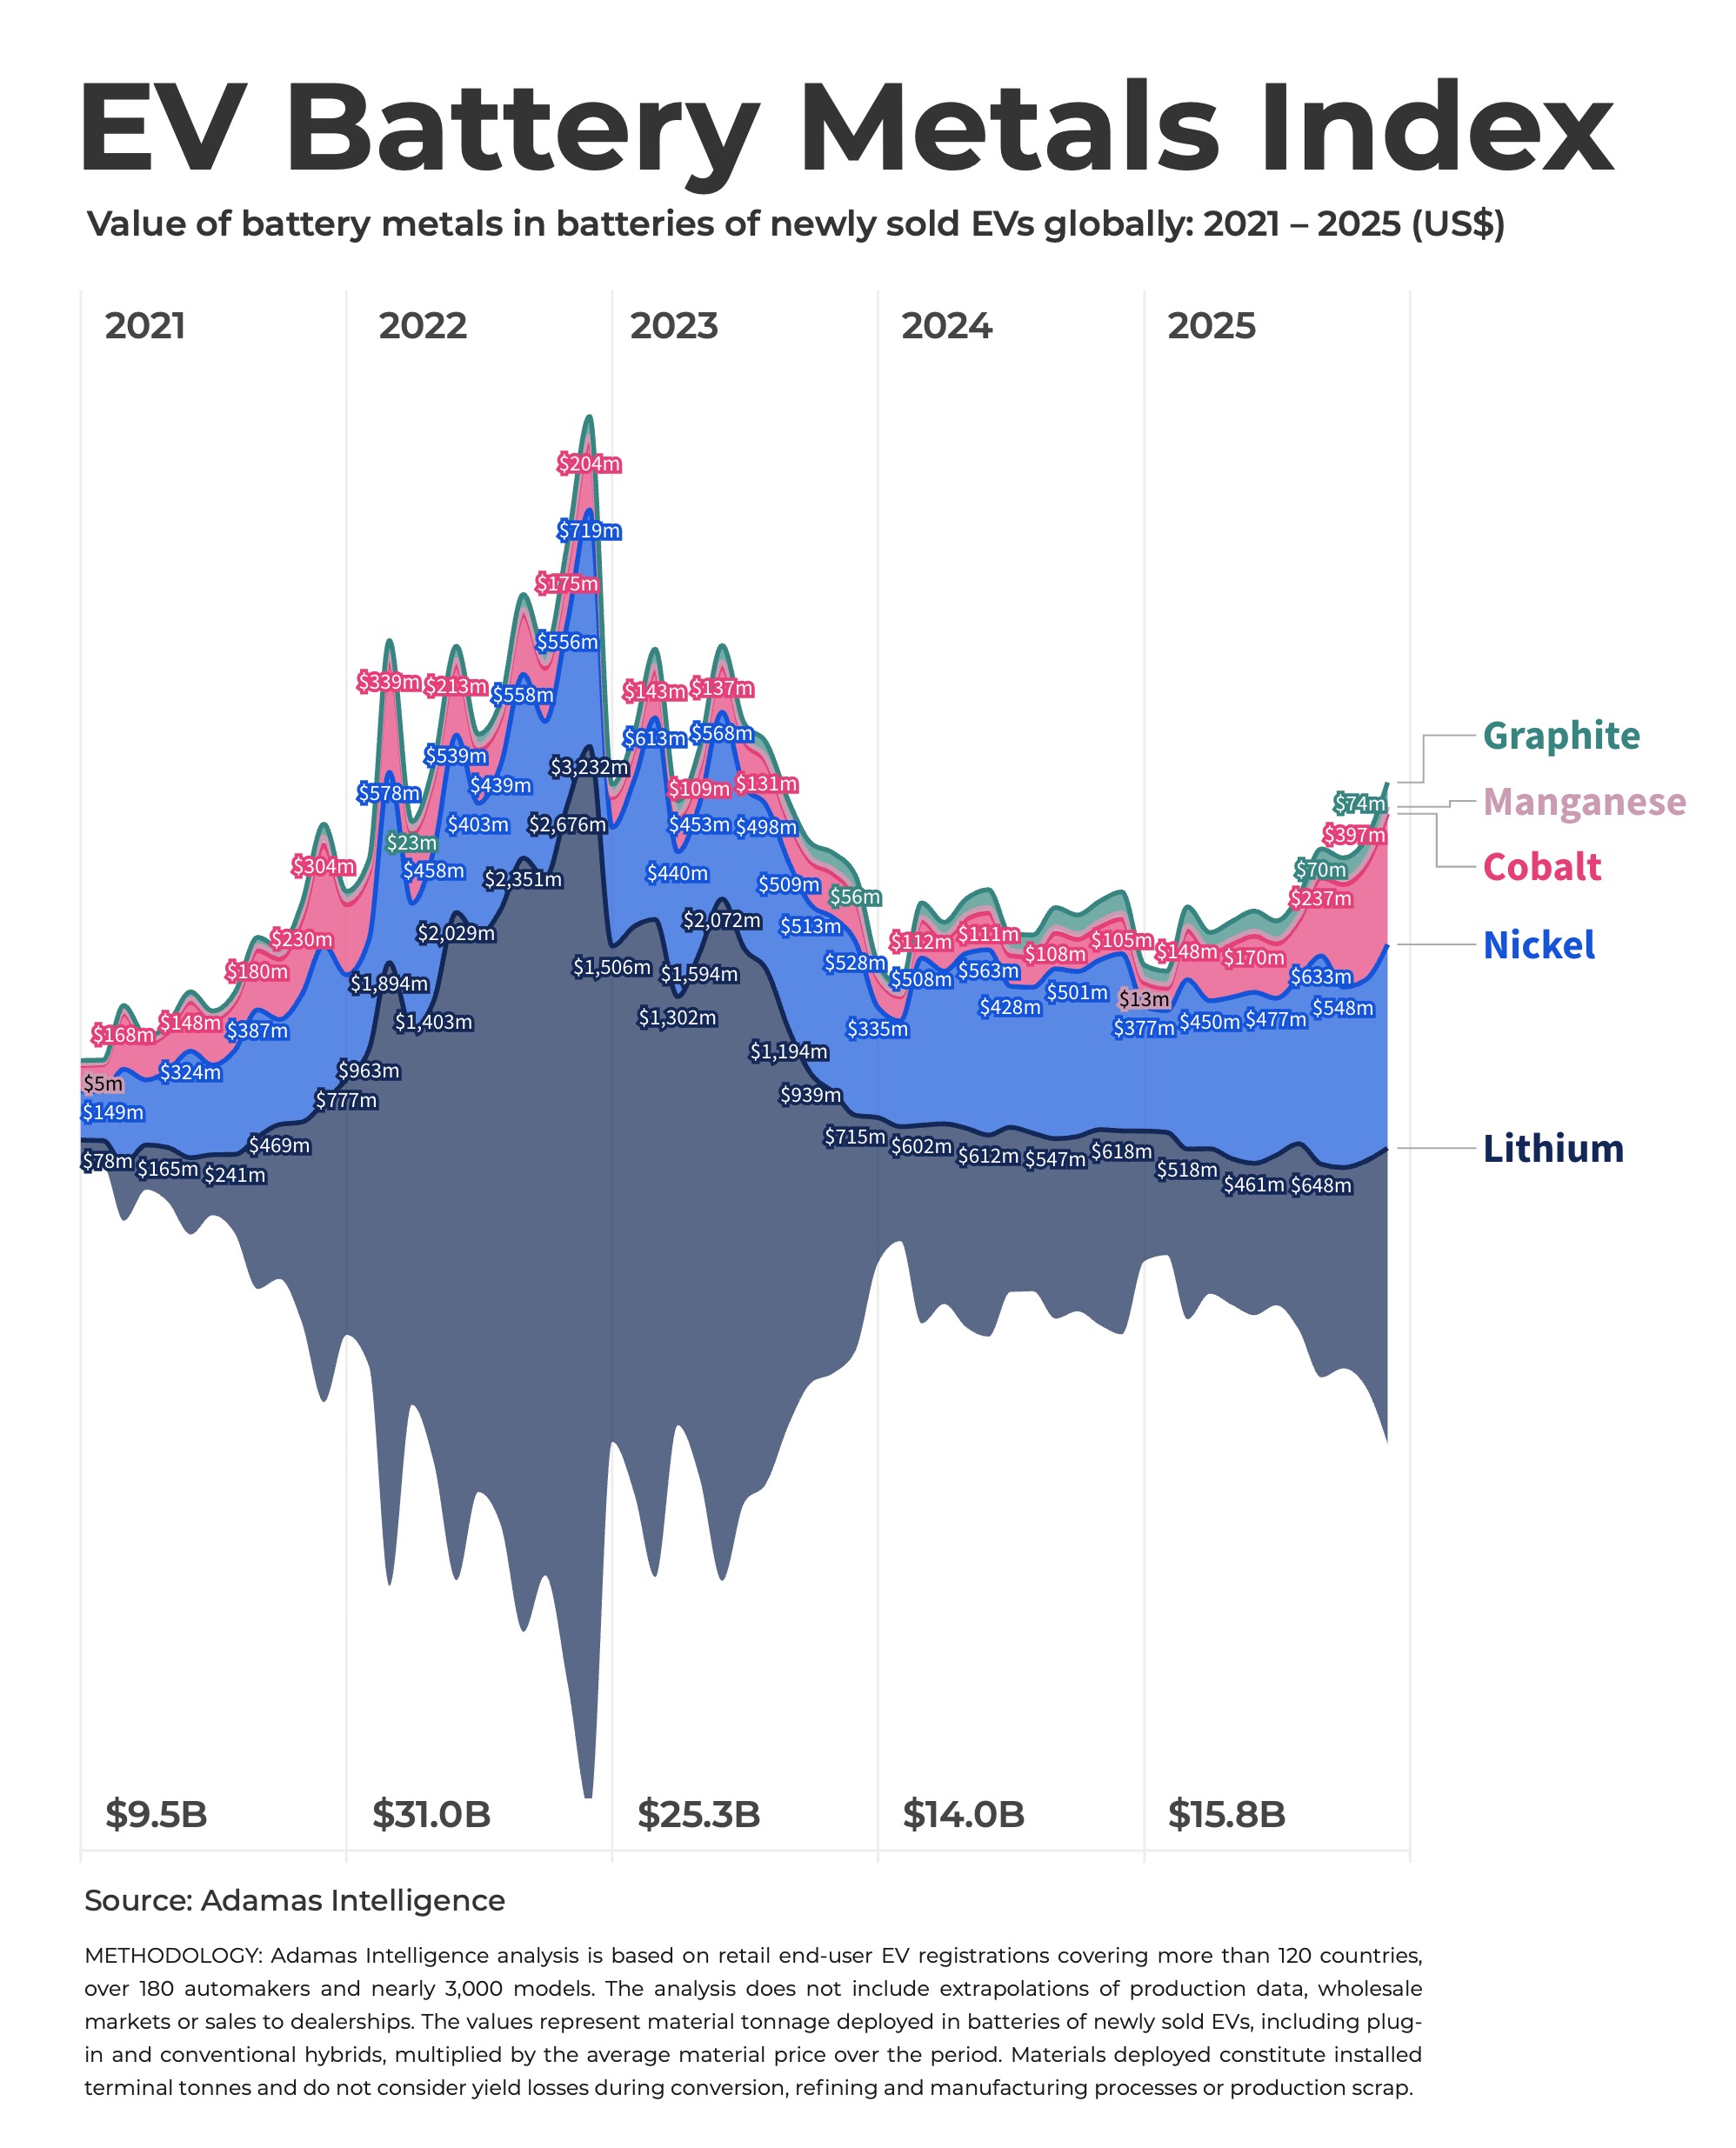
    EV raw material spend for lithium, graphite, nickel, cobalt and manganese in newly sold passenger EVs reached $15.8 billion in 2025, up 13% year on year, with December’s monthly bill topping $2 billion for the first time since August 2023 as lithium hydroxide/carbonate and nickel sulphate prices climbed. Global EV battery capacity deployment is on track to exceed 1 TWh in 2025, nearly quadruple 2021’s 286 GWh, with LFP packs accounting for almost 50% of capacity and 83% of LFP roll-out concentrated in China. Cobalt’s share of the EV Metal Index rebounded to 14% ($2.4 billion) on >200% year-on-year sulphate price gains, while nickel and lithium each surpassed $6 billion in contained value, supported by high‑nickel NCM chemistries in the US and Europe despite growing LFP penetration.

    Technical Brief

    • EV Metal Index couples contained metal tonnages with prevailing battery‑grade prices to quantify value flow.
    • Battery capacity deployment grew 25% year‑on‑year, outpacing the 20% growth in EV unit sales.
    • Market size in GWh terms is now roughly four times 2021 and ten times 2019 levels.
    • Cobalt sulphate prices were over 200% higher year‑on‑year by December, sharply lifting cobalt’s index share.
    • Installed metal tonnage excludes processing, conversion and scrap losses, where yield losses often reach double‑digit percentages.

    Our Take

    The sharp rebound in cobalt sulphate pricing and its index share in 2025 contrasts with several energy-transition pieces in our database where cobalt was being de-emphasised in favour of LFP and manganese-rich chemistries, suggesting high-nickel and mid-nickel cathodes are proving more resilient than many OEM roadmaps implied.

    With LFP already near 50% of global battery capacity and China accounting for 83% of that roll-out, the low LFP penetration in the USA (6%) and Europe (12%) implies significant room for chemistry substitution that could structurally cap lithium and nickel price upside for new projects in those regions.

    Tesla’s 40% use of LFP on a GWh basis alongside CATL’s dominance in mid-nickel cathodes positions Chinese supply chains as the swing factor for both lithium and nickel demand, which aligns with other BYD-focused items in our coverage showing Chinese battery and EV makers increasingly shaping upstream investment signals outside China.

    Geotechnical Software for Modern Teams

    Centralise site data, logs, and lab results with GEODB-io, CMRR-io, and HYDROGEO-io.

    No credit card required.

    • Save and export unlimited calculations
    • Advanced data visualisation
    • Generate professional PDF reports
    • Cloud storage for all your projects

    Prepared by collating external sources, AI-assisted tools, and Geomechanics.io’s proprietary mining database, then reviewed for technical accuracy & edited by our geotechnical team.

    Related Articles
    Fortescue copper–arsenic Toowong Process: project economics lens for mine planners
    Mining
    about 11 hours ago

    Fortescue copper–arsenic Toowong Process: project economics lens for mine planners

    Fortescue has sold more than 40 tonnes of copper concentrate treated with its patented Toowong Process, a low-temperature, low-pressure hydrometallurgical circuit that removes arsenic from copper concentrates. Developed and tested over four years after Fortescue acquired the technology, the process targets a longstanding penalty element constraint that limits saleability of high-arsenic ores. Commercial deployment could materially change project economics for arsenic-rich copper deposits, enabling miners to convert previously marginal or stranded resources into exportable concentrate streams.

    Core’s Finniss lithium: 92 m Blackbeard hit and what it means for mine design
    Mining
    about 11 hours ago

    Core’s Finniss lithium: 92 m Blackbeard hit and what it means for mine design

    Core Lithium has reported its longest mineralised downhole intersection at the Blackbeard prospect within the Finniss lithium operation in the Northern Territory, with diamond drillhole NMRD104 returning 92m at 1.25 per cent Li₂O, including 73m at 1.45 per cent Li₂O. The thick, continuous spodumene-bearing pegmatite materially extends known mineralisation at depth and along strike, improving the potential for larger, more coherent underground or bulk open-pit mine designs. For resource modellers and geotechs, the interval supports tighter geological domaining and may justify updated pit shells and geotechnical slope assessments.

    South32 Australian manganese output lift: throughput takeaways for mine planners
    Mining
    about 11 hours ago

    South32 Australian manganese output lift: throughput takeaways for mine planners

    South32 lifted Australia Manganese saleable output 15 per cent quarter-on-quarter to 902,000 wet metric tonnes in the September 2026 quarter, driven by higher utilisation of the primary processing circuit, while keeping full-year production guidance unchanged across its operations. Alumina production also increased, and the company is continuing capital deployment into base metals growth projects, including copper and zinc developments. For mine planners and process engineers, the numbers signal more stable plant throughput assumptions and sustained demand for processing circuit optimisation and debottlenecking work.

    Related Industries & Products

    Mining

    Geotechnical software solutions for mining operations including CMRR analysis, hydrogeological testing, and data management.

    CMRR-io

    Streamline coal mine roof stability assessments with our cloud-based CMRR software featuring automated calculations, multi-scenario analysis, and collaborative workflows.

    HYDROGEO-io

    Comprehensive hydrogeological testing platform for managing, analysing, and reporting on packer tests, lugeon values, and hydraulic conductivity assessments.

    GEODB-io

    Centralised geotechnical data management solution for storing, accessing, and analysing all your site investigation and material testing data.

    AllGeotechnicalInfrastructureHazardsEnvironmental