Tintina’s C$91M Domeyko funding: capex, NPV and schedule notes for mine planners
Reviewed by Tom Sullivan
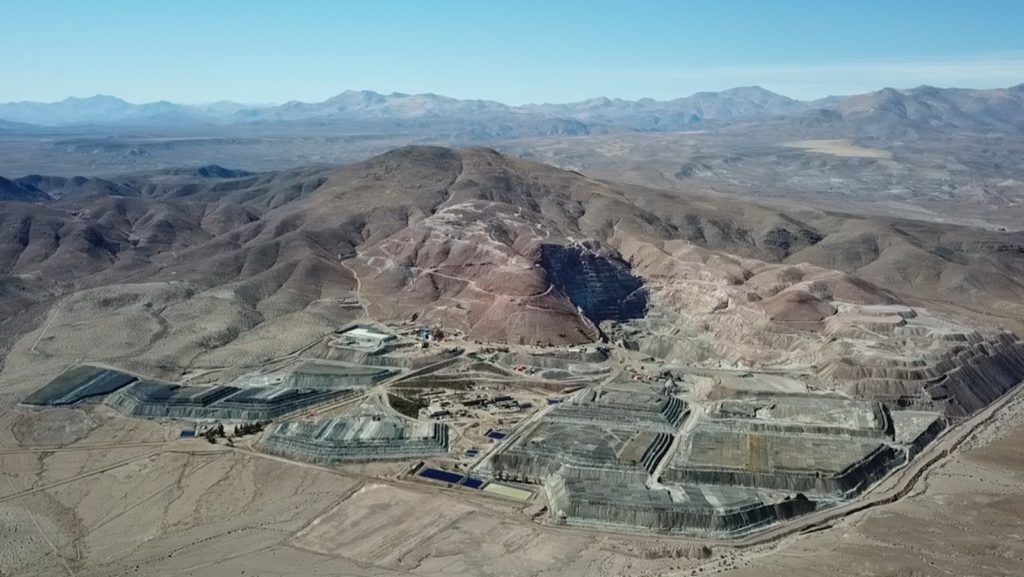
First reported on MINING.com
30 Second Briefing
Tintina Mines has secured C$91 million in private placement funding, led by Sumitomo Corp. and the Gignac family via a new investment vehicle taking C$48 million of first‑tranche receipts and potentially 38% ownership after warrant exercise, with Franco‑Nevada contributing C$14 million. About C$55 million will advance the Domeyko Sulfuros copper‑gold porphyry in Chile’s Atacama Region to a final investment decision and C$36 million will buy out the remaining 26.25% project stake, implying a C$138 million pre‑money valuation. Domeyko’s PEA outlines a 25‑year open pit producing 37,000 t/y copper and 57,000 oz/y gold in concentrate from 100.8 Mt M&I at 0.35% Cu and 0.28 g/t Au, with initial capex of $1.28 billion and after‑tax NPV8 of $328 million.
Technical Brief
- Subscription receipts are priced at C$0.68, issued in two tranches with different security structures.
- First tranche totals C$62 million and includes both common shares and warrants in Tintina.
- Second tranche raises C$29 million and comprises only common shares, no attached warrants.
- Full warrant exercise on the first tranche could add ~C$82 million of follow‑on capital.
- Minority Domeyko Sulfuros holders currently own 26.25%, to be fully bought out with C$36 million.
- Tintina’s market capitalisation jumped to C$216.3 million after the announcement, with shares peaking at C$1.70.
- Post‑transaction, chairman/CEO Juan Enrique Rassmuss’ stake is expected at 47%, potentially diluting to 36% with warrant exercise.
- A new Sumitomo–Gignac investment vehicle will acquire C$48 million of first‑tranche receipts, targeting 25–38% ownership.
Our Take
With an initial capital requirement of C$1.28 billion against an after-tax NPV8 of C$328 million, Domeyko Sulfuros in Chile’s Atacama Region screens as a relatively high-capex, moderate-return porphyry, implying Tintina Mines will likely need either improved economics at PFS or creative project finance (e.g. streaming or larger JV) to secure full build funding.
The planned buyout of the 26.25% minority stake at a C$138 million pre-money project valuation consolidates control for Tintina Mines’ Chilean backers, which typically simplifies later-stage debt negotiations with lenders that prefer a single dominant sponsor in Latin American copper projects.
In our mining database, copper-gold items tagged to Chile and Latin America frequently feature larger incumbents, so Sumitomo Corp. and Franco-Nevada appearing at this early PEA-stage signals that Domeyko Sulfuros is being positioned for eventual scale-up or potential handover to a major once key de-risking milestones are met.
Prepared by collating external sources, AI-assisted tools, and Geomechanics.io’s proprietary mining database, then reviewed for technical accuracy & edited by our geotechnical team.
Related Articles


Related Industries & Products
Mining
Geotechnical software solutions for mining operations including CMRR analysis, hydrogeological testing, and data management.
CMRR-io
Streamline coal mine roof stability assessments with our cloud-based CMRR software featuring automated calculations, multi-scenario analysis, and collaborative workflows.
HYDROGEO-io
Comprehensive hydrogeological testing platform for managing, analysing, and reporting on packer tests, lugeon values, and hydraulic conductivity assessments.
GEODB-io
Centralised geotechnical data management solution for storing, accessing, and analysing all your site investigation and material testing data.