USA Rare Earth South Carolina plant: mine‑to‑magnet chain risks for engineers
Reviewed by Joe Ashwell
First reported on MINING.com
30 Second Briefing
USA Rare Earth will invest $1.2 billion in a rare earth metals and NdFeB magnet plant at Bailey Industrial Park, Blacksburg, South Carolina, targeting 6,400 tpa of sintered NdFeB magnets and 5,000 tpa of strip-cast metal and alloy, with commissioning from 2028. Together with an expanded Stillwater, Oklahoma facility, US domestic capacity is expected to reach 10,000 tpa of NdFeB magnets and 10,000 tpa of heavy rare earth strip-cast metal and alloy, fed by the Round Top project in Texas and the proposed Serra Verde acquisition in Brazil. The vertically integrated mine-to-magnet chain faces regulatory scrutiny in Brazil, a contested $1.58 billion CHIPS-backed funding package, and a technology theft lawsuit from MP Materials.
Technical Brief
- Engineering design and long-lead equipment procurement for the Blacksburg plant are already underway ahead of site works.
- Site preparation in Bailey Industrial Park, Cherokee County, is scheduled to start within “coming months”.
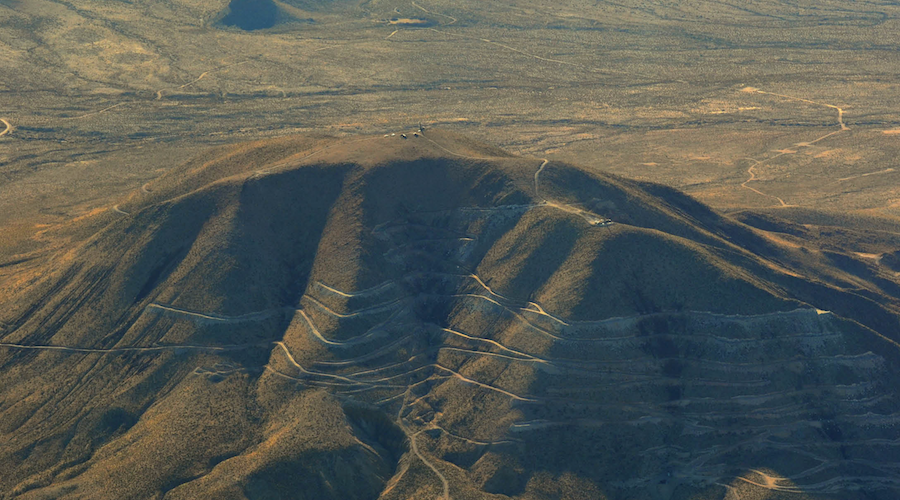
- The integrated chain includes Round Top heavy rare earth mining/processing in Sierra Blanca, Texas, as upstream feed.
- Planned upstream supply is further diversified via the proposed acquisition of Serra Verde’s producing rare earth mine in Goiás, Brazil.
- Additional midstream capacity comes from the LCM metal/alloy plant in Cheshire, UK, and a planned metallisation/alloy facility in Lacq, France.
- A non‑binding CHIPS LOI would provide up to $1.58 billion (US$277m grant, US$1.3b loan) for equity of 8–16%.
- Brazil’s antitrust authority has opened a competition investigation into the Serra Verde transaction, adding regulatory timing risk.
- MP Materials has filed a lawsuit alleging theft of proprietary magnet technology via an ex‑employee, which USAR disputes.
Our Take
The planned South Carolina neodymium-iron-boron magnet facility gives USA Rare Earth a downstream anchor in the US just as Cade in Brazil reviews its proposed $2.8 billion acquisition of Serra Verde, which our coverage notes could supply up to half of ex-China heavy rare earth output by next year.
With USA Rare Earth already selected for up to $19.3 million in US Department of Energy funding for a pilot rare earth processing project, the $1.2 billion Blacksburg build positions the company to argue for broader federal backing as Washington seeks to counter China’s near-total dominance of rare earth processing highlighted in recent BMI analysis.
MP Materials’ ongoing lawsuit over alleged misappropriation of magnet technology means any process route USA Rare Earth deploys at Bailey Industrial Park will likely be scrutinised closely by competitors and policymakers, especially given the CHIPS-linked option for the US government to take an 8–16% equity stake in the company.
Prepared by collating external sources, AI-assisted tools, and Geomechanics.io’s proprietary mining database, then reviewed for technical accuracy & edited by our geotechnical team.
Related Articles


Related Industries & Products
Mining
Geotechnical software solutions for mining operations including CMRR analysis, hydrogeological testing, and data management.
CMRR-io
Streamline coal mine roof stability assessments with our cloud-based CMRR software featuring automated calculations, multi-scenario analysis, and collaborative workflows.
HYDROGEO-io
Comprehensive hydrogeological testing platform for managing, analysing, and reporting on packer tests, lugeon values, and hydraulic conductivity assessments.
GEODB-io
Centralised geotechnical data management solution for storing, accessing, and analysing all your site investigation and material testing data.