IGO sees no path forward for WA lithium refinery: cost and margin lessons for mines
Reviewed by Joe Ashwell
First reported on MINING.com
30 Second Briefing
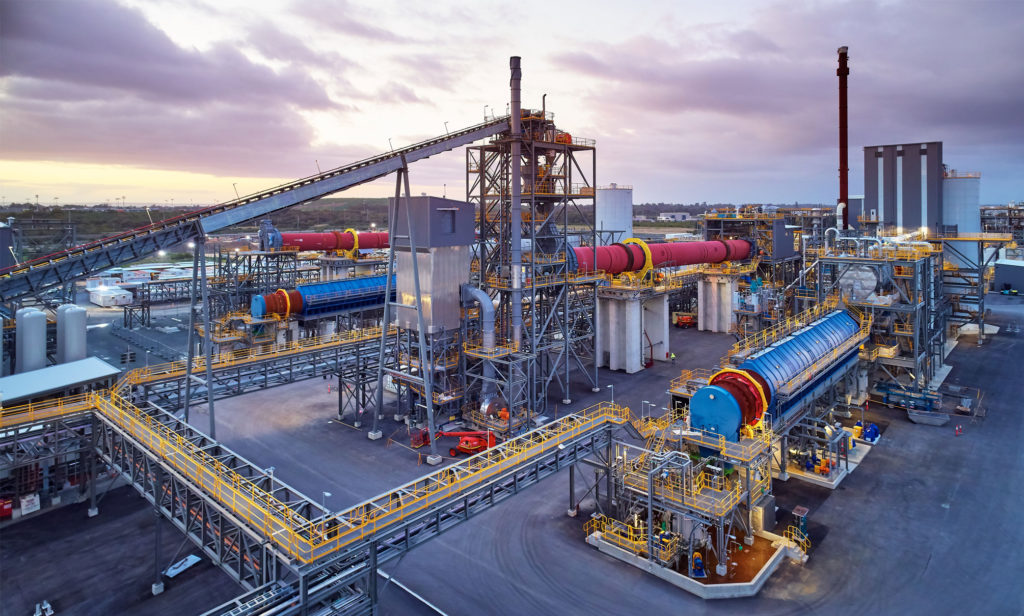
IGO has ruled out any viable path for the Kwinana lithium hydroxide refinery in Western Australia, after three years of operation delivered only 35% of nameplate capacity on average and a September-quarter EBITDA loss of A$19.6 million despite lifting output to 2,775 tonnes at A$14,177/t conversion cost. CEO Ivan Vella cited structurally high Australian energy and labour costs and the lack of downstream processing clusters, arguing that even at full nameplate the asset would remain uneconomic. By contrast, TLEA’s 51%-owned Greenbushes mine produced 1.48Mt of spodumene concentrate at A$325/t, generating A$1.5 billion cashflow and a 66% EBITDA margin, with Chemical Grade Plant 3 set to add 500,000t/y capacity by year-end.
Technical Brief
- Train 2 construction at Kwinana has been suspended, with only Train 1 partially operating.
- IGO has already booked a A$605 million impairment against the Kwinana refinery asset.
- Ownership of Kwinana sits within Tianqi Lithium Energy Australia, 51% Tianqi Lithium and 49% IGO.
- Tianqi has publicly stated it has no plans to suspend refinery operations, despite IGO’s stance.
- IGO reports ongoing, complex JV negotiations with Tianqi over both Train 1 operations and Train 2’s future.
- Management describes Kwinana as a “challenged asset” even after global benchmarking against other lithium hydroxide plants.
- Structural cost issues cited include high Australian energy and labour costs and absence of downstream processing clusters.
Our Take
With Greenbushes generating A$1.5 billion in cashflow at unit costs of A$325/t and a 66% EBITDA margin, the contrast to Kwinana’s A$19.6 million quarterly EBITDA loss underlines why upstream spodumene concentrate exposure in Western Australia currently looks far more defensible than downstream hydroxide refining in our mining project coverage.
The A$605 million impairment at the Kwinana lithium refinery effectively prices in a structural cost disadvantage of roughly 2–3x versus peers, signalling that any future restart or repurposing would likely require either subsidised power/chemicals in WA or a step-change in process design rather than incremental debottlenecking.
The presence of a 13Mt measured and indicated tungsten trioxide resource in Portugal in the same portfolio highlights that IGO and its partners are not purely lithium‑dependent, which in our database tends to give operators more room to mothball or rationalise high-cost lithium assets without jeopardising group-level cashflow stability.
Prepared by collating external sources, AI-assisted tools, and Geomechanics.io’s proprietary mining database, then reviewed for technical accuracy & edited by our geotechnical team.
Related Articles

Related Industries & Products
Mining
Geotechnical software solutions for mining operations including CMRR analysis, hydrogeological testing, and data management.
Construction
Quality control software for construction companies with material testing, batch tracking, and compliance management.
CMRR-io
Streamline coal mine roof stability assessments with our cloud-based CMRR software featuring automated calculations, multi-scenario analysis, and collaborative workflows.
HYDROGEO-io
Comprehensive hydrogeological testing platform for managing, analysing, and reporting on packer tests, lugeon values, and hydraulic conductivity assessments.
GEODB-io
Centralised geotechnical data management solution for storing, accessing, and analysing all your site investigation and material testing data.