Geomechanics.io

  • Free Tools
Sign UpLog In
Built byBoxcut Studio

Geomechanics.io

Geomechanics, Streamlined.

© 2026 Geomechanics.io. All rights reserved.

Geomechanics.io

CMRR-ioGEODB-ioHYDROGEO-ioQCDB-ioFree Tools & CalculatorsBlogLatest Industry News

Industries

MiningConstructionTunnelling

Company

Terms of UsePrivacy PolicyLinkedIn
    Projects

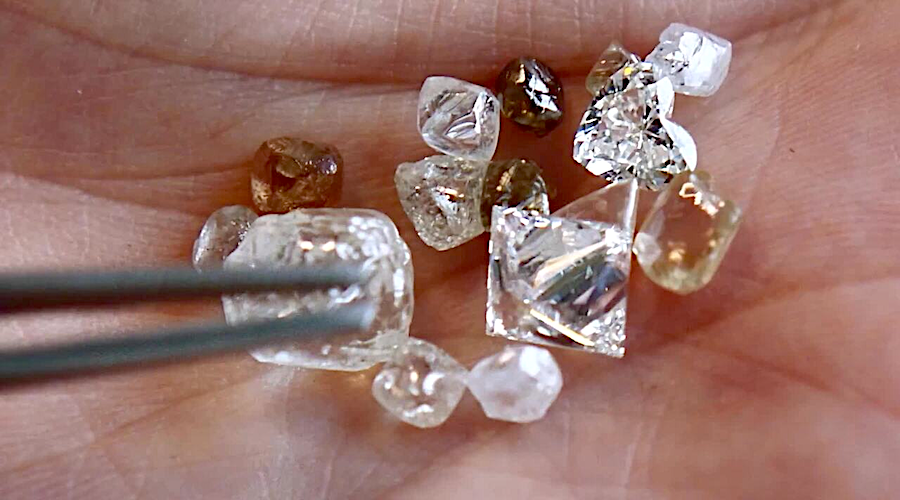
    De Beers diamond price reset and sightholder cuts: key takeaways for mine planners

    July 8, 2026|

    Reviewed by Joe Ashwell

    De Beers diamond price reset and sightholder cuts: key takeaways for mine planners

    First reported on MINING.com

    30 Second Briefing

    De Beers has sharply cut official rough diamond prices at its July sales cycle and reduced its sightholder list from about 70 to roughly 45–50, abandoning a long-standing strategy of pricing 5%–50% above the secondary market. The Anglo American unit has also moved to one-line invoicing and altered box assortments, obscuring exact per-carat reductions while reallocating supply towards its strongest customers. The reset comes amid weak Chinese luxury demand, surging laboratory-grown output, increased rough supply from Angola and Anglo’s ongoing attempt to sell the business.

    Technical Brief

    • One-line invoicing now gives sightholders only a single total per sale, eliminating box-level pricing visibility.
    • Altered box assortments change stone size/quality mixes, preventing like-for-like per-carat price comparisons.
    • De Beers is responding to additional rough supply entering the market from Angola and other producers.
    • US tariffs and conflict in the Middle East are adding demand and trading uncertainty for downstream buyers.
    • Previous practice of maintaining high official prices while granting private discounts is becoming harder to sustain under current volatility.
    • For other bulk commodity markets, similar opaque invoicing and re-assortment tactics complicate benchmarking, hedging and contract indexation.

    Our Take

    Anglo American’s move to sell De Beers, noted in our database since May 2024, means these rough diamond price cuts and the reduction from about 70 to 45–50 sightholders are likely being read by bidders as an attempt to stabilise margins and clean up the sales book ahead of a transaction.

    Botswana’s efforts to secure sovereign wealth backing to buy a controlling stake in De Beers, highlighted in the June 2026 coverage, suggest producer countries will be watching these pricing changes closely, as lower rough prices can depress government royalty and dividend flows in the short term even if they support long‑term demand.

    With other recent De Beers coverage showing Gen Z driving a rebound in US natural diamond demand, the current discounting of rough diamonds may be interpreted by downstream manufacturers as a temporary reset rather than a structural collapse, giving them scope to rebuild inventories at more sustainable input costs.

    Geotechnical Software for Modern Teams

    Centralise site data, logs, and lab results with GEODB-io, CMRR-io, and HYDROGEO-io.

    No credit card required.

    • Save and export unlimited calculations
    • Advanced data visualisation
    • Generate professional PDF reports
    • Cloud storage for all your projects

    Prepared by collating external sources, AI-assisted tools, and Geomechanics.io’s proprietary mining database, then reviewed for technical accuracy & edited by our geotechnical team.

    Related Articles
    Geopolitical risk and private capital flows: gold price signals for mine planners
    Mining
    about 11 hours ago

    Geopolitical risk and private capital flows: gold price signals for mine planners

    Growing geopolitical tensions are pushing capital out of sovereign bonds and into private assets, a rotation market-cycle analyst Martin Armstrong links to a potential renewed gold rally from Q1 next year. Armstrong sees Europe as particularly exposed, arguing EU states face rising war-related borrowing costs and inflation as “war drums” lift long-term rates, while bond markets “give us the real story”. He warns that if gold closes below $4,000/oz weekly it could test $3,500–$3,700, but expects elections in the US, Israel and Ukraine to keep geopolitical risk elevated and ultimately drive prices higher.

    McEwen’s $55M Ontario asset sale: production growth lens for mine planners
    Mining
    2 days ago

    McEwen’s $55M Ontario asset sale: production growth lens for mine planners

    McEwen has agreed to sell its Fuller and Paymaster gold properties in Ontario’s Timmins district to Discovery Mining for $55 million in cash and stock, freeing capital to push a production target of 250,000–300,000 gold-equivalent ounces per year by 2030. The deal covers 210 hectares at Fuller, a 60% stake in the 179-hectare Paymaster property, and associated surface rights, consolidating Paymaster under Discovery’s Dome Mine subsidiary. Proceeds will be reinvested into the Fox Complex (Froome, Stock, Grey Fox), Nevada’s Gold Bar Complex, and Mexico’s El Gallo build, with Stock Mine slated for first ore in Q4 2026 and commercial output in Q1 2027.

    Lithium Triangle extraction hurdles: hydrogeological insights for project teams
    Mining
    2 days ago

    Lithium Triangle extraction hurdles: hydrogeological insights for project teams

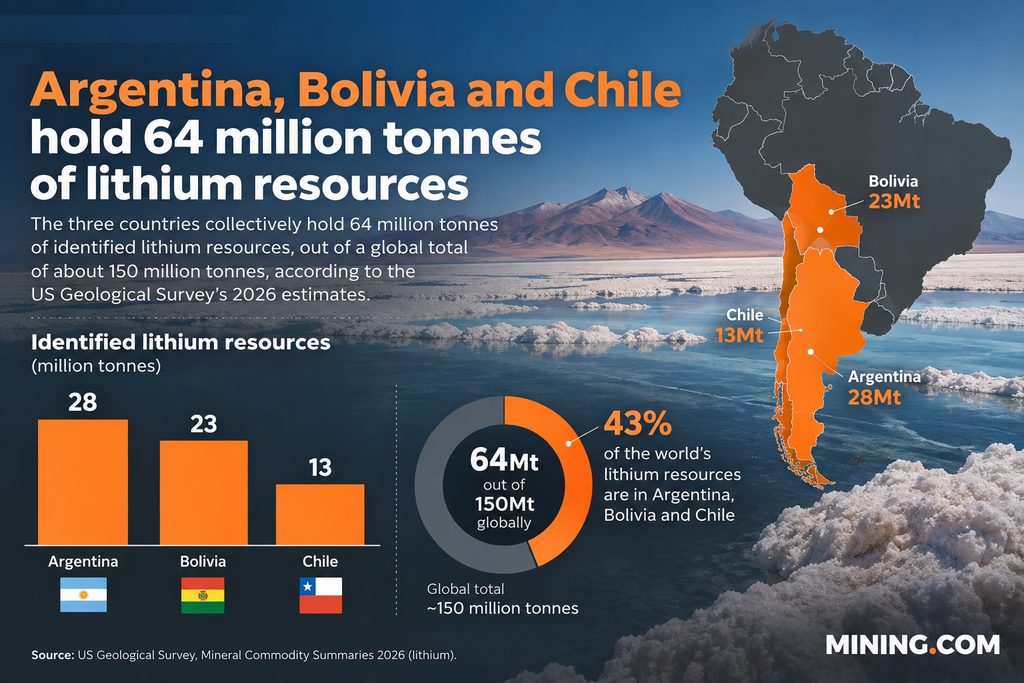
    South America’s Lithium Triangle holds about 64 million tonnes of identified lithium resources (43% of the global 150 million tonnes), yet geologist José Cabello’s review of 43 salt flats across Argentina, Bolivia and Chile shows that variable brine chemistry, impurities and groundwater behaviour make recovery and costs highly site-specific. Salar de Atacama benefits from ultra‑dry climate, relatively clean brines and strong logistics, while other basins such as Altoandinos, Pedernales, Hombre Muerto Oeste, Rincón, Sal de los Ángeles and Sal de Vida face tighter water and hydrogeological constraints. Direct lithium extraction (DLE) could unlock lower‑grade or impurity‑rich brines, but Cabello stresses that trade‑offs between brine withdrawal and freshwater consumption mean technology selection must be tailored to each basin’s hydrology and ecosystem.

    Related Industries & Products

    Mining

    Geotechnical software solutions for mining operations including CMRR analysis, hydrogeological testing, and data management.

    CMRR-io

    Streamline coal mine roof stability assessments with our cloud-based CMRR software featuring automated calculations, multi-scenario analysis, and collaborative workflows.

    HYDROGEO-io

    Comprehensive hydrogeological testing platform for managing, analysing, and reporting on packer tests, lugeon values, and hydraulic conductivity assessments.

    GEODB-io

    Centralised geotechnical data management solution for storing, accessing, and analysing all your site investigation and material testing data.

    AllGeotechnicalInfrastructureHazardsEnvironmental