Central Asia Metals–Cygnus deal: project pipeline and PEA lens for mine planners
Reviewed by Joe Ashwell
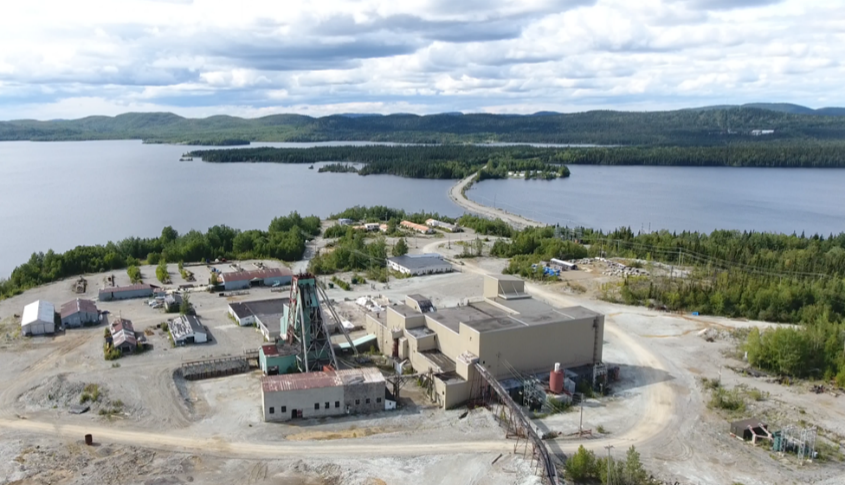
First reported on MINING.com
30 Second Briefing
Central Asia Metals is acquiring Cygnus Metals for about A$232 million ($166 million) via an all-share offer at 0.06 CAML shares per Cygnus share, a 60% premium to Cygnus’ last close, adding the Chibougamau copper-gold project in Québec and lithium ground in the James Bay district plus rare earth and base metal projects in Western Australia. Chibougamau carries measured and indicated resources of roughly 149,000 tonnes copper and 167,000 oz gold (plus 182,000 tonnes copper and 454,000 oz gold inferred) and a historical 900,000 t/y plant, with CAML planning an updated PEA and feasibility work. CAML, which currently produces 12,000–13,000 t/y copper cathode and 18,000–20,000 t/y zinc-in-concentrate plus 26,000–28,000 t/y lead-in-concentrate from Sasa (North Macedonia) and Kounrad (Kazakhstan), will seek a TSX or TSXV listing to support North American funding and visibility.
Technical Brief
- Share exchange set at 0.06 new CAML shares per Cygnus share, all-scrip consideration.
- Implied offer price is A$0.176 per Cygnus share, based on CAML’s 1 June closing price.
- Premium equates to 60% over Cygnus’ last close of A$0.11 and 40% over 20‑day VWAP.
- Post‑transaction ownership split targeted at ~70% CAML shareholders and ~30% Cygnus shareholders.
- Cygnus shareholder scheme meeting targeted for September, requiring 75% approval threshold to proceed.
- CAML must also secure its own shareholder approval to issue new shares and options for the deal.
- Chibougamau resource base derives from a 2022 PEA by Doré Copper Mining Corp., informing current planning.
- Existing 900,000 t/y processing plant at Chibougamau offers brownfield restart potential rather than greenfield build.
- CAML cites in‑house experience with underground mining, dry stack tailings and concentrate production as key to de‑risking development.
Our Take
CAML’s move into the Chibougamau copper-gold project in central Québec gives it exposure to a Canadian jurisdiction that, in our database, has seen a higher rate of project approvals and infrastructure support than many other North American copper regions, which can materially de-risk first-time entrants from the UK and Central Asia.
The all-share structure with roughly 70% post-deal ownership for existing Central Asia Metals shareholders and 30% for Cygnus holders effectively turns Cygnus into CAML’s North American growth platform, a pattern seen in several other copper M&A items where juniors contribute geology and majors contribute balance sheet and operating teams.
With copper and gold among the most frequently tagged commodities in our 1180 Mining stories, CAML’s diversification from the Sasa zinc-lead and Kounrad copper operations into Québec and the James Bay district positions it alongside other multi-asset copper players that are using M&A rather than greenfield exploration to secure pipeline ounces and pounds.
Prepared by collating external sources, AI-assisted tools, and Geomechanics.io’s proprietary mining database, then reviewed for technical accuracy & edited by our geotechnical team.
Related Articles


Related Industries & Products
Mining
Geotechnical software solutions for mining operations including CMRR analysis, hydrogeological testing, and data management.
Construction
Quality control software for construction companies with material testing, batch tracking, and compliance management.
CMRR-io
Streamline coal mine roof stability assessments with our cloud-based CMRR software featuring automated calculations, multi-scenario analysis, and collaborative workflows.
HYDROGEO-io
Comprehensive hydrogeological testing platform for managing, analysing, and reporting on packer tests, lugeon values, and hydraulic conductivity assessments.
GEODB-io
Centralised geotechnical data management solution for storing, accessing, and analysing all your site investigation and material testing data.