Geomechanics.io

  • Free Tools
Sign UpLog In
Built byBoxcut Studio

Geomechanics.io

Geomechanics, Streamlined.

© 2026 Geomechanics.io. All rights reserved.

Geomechanics.io

CMRR-ioGEODB-ioHYDROGEO-ioQCDB-ioFree Tools & CalculatorsBlogLatest Industry News

Industries

MiningConstructionTunnelling

Company

Terms of UsePrivacy PolicyLinkedIn
    Projects

    Mining stocks’ $206bn fortnight: capex and project signals for engineers

    August 14, 2026|

    Reviewed by Joe Ashwell

    Mining stocks’ $206bn fortnight: capex and project signals for engineers

    First reported on MINING.com

    30 Second Briefing

    Mining’s 50 largest listed companies have added $206 billion in market value over the past two weeks, outpacing the year‑to‑date performance of the US “Magnificent 7” tech stocks. The combined valuation of the top miners, however, still sits at roughly one‑tenth of big tech’s aggregate capitalisation, underlining how cheaply large‑scale copper, iron ore, coal and battery‑metal producers continue to trade relative to growth equities. For project developers and contractors, stronger balance sheets at majors signal more room for capex on new pits, tailings expansions and processing upgrades.

    Technical Brief

    • Valuation gap implies majors are still priced closer to cyclicals than to growth equities.
    • Balance‑sheet strengthening at diversified houses improves debt capacity for multi‑billion‑dollar project pipelines.
    • Contractors can expect improved payment security and potentially longer‑tenor EPCM and mining services contracts.
    • For project sanctioning, higher equity valuations reduce dilution pressure on large brownfield expansion raises.
    • Trend suggests increased competition for high‑quality copper, iron ore and coal project acquisitions.

    Geotechnical Software for Modern Teams

    Centralise site data, logs, and lab results with GEODB-io, CMRR-io, and HYDROGEO-io.

    No credit card required.

    • Save and export unlimited calculations
    • Advanced data visualisation
    • Generate professional PDF reports
    • Cloud storage for all your projects

    Prepared by collating external sources, AI-assisted tools, and Geomechanics.io’s proprietary mining database, then reviewed for technical accuracy & edited by our geotechnical team.

    Related Articles

    McEwen’s $55M Ontario asset sale: production growth lens for mine planners
    Mining
    about 14 hours ago

    McEwen’s $55M Ontario asset sale: production growth lens for mine planners

    McEwen has agreed to sell its Fuller and Paymaster gold properties in Ontario’s Timmins district to Discovery Mining for $55 million in cash and stock, freeing capital to push a production target of 250,000–300,000 gold-equivalent ounces per year by 2030. The deal covers 210 hectares at Fuller, a 60% stake in the 179-hectare Paymaster property, and associated surface rights, consolidating Paymaster under Discovery’s Dome Mine subsidiary. Proceeds will be reinvested into the Fox Complex (Froome, Stock, Grey Fox), Nevada’s Gold Bar Complex, and Mexico’s El Gallo build, with Stock Mine slated for first ore in Q4 2026 and commercial output in Q1 2027.

    Lithium Triangle extraction hurdles: hydrogeological insights for project teams
    Mining
    about 14 hours ago

    Lithium Triangle extraction hurdles: hydrogeological insights for project teams

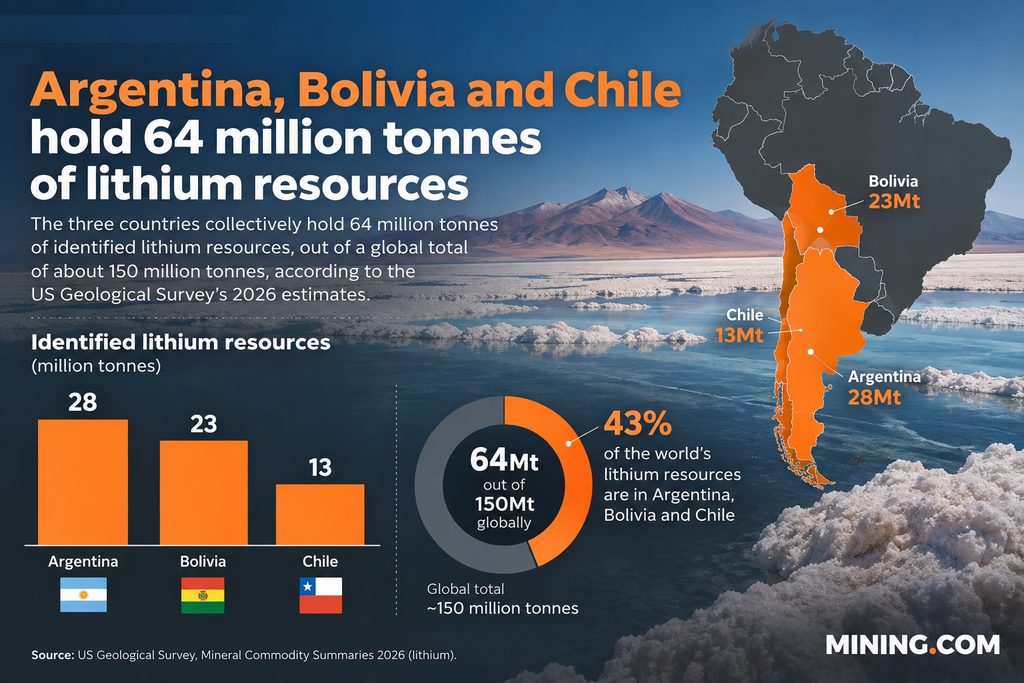
    South America’s Lithium Triangle holds about 64 million tonnes of identified lithium resources (43% of the global 150 million tonnes), yet geologist José Cabello’s review of 43 salt flats across Argentina, Bolivia and Chile shows that variable brine chemistry, impurities and groundwater behaviour make recovery and costs highly site-specific. Salar de Atacama benefits from ultra‑dry climate, relatively clean brines and strong logistics, while other basins such as Altoandinos, Pedernales, Hombre Muerto Oeste, Rincón, Sal de los Ángeles and Sal de Vida face tighter water and hydrogeological constraints. Direct lithium extraction (DLE) could unlock lower‑grade or impurity‑rich brines, but Cabello stresses that trade‑offs between brine withdrawal and freshwater consumption mean technology selection must be tailored to each basin’s hydrology and ecosystem.

    KGHM’s $2.4bn copper projects fast-tracked: CRMA implications for mine planners
    Mining
    about 14 hours ago

    KGHM’s $2.4bn copper projects fast-tracked: CRMA implications for mine planners

    EU regulators have granted strategic status under the Critical Raw Materials Act to KGHM’s 9.5‑billion‑zloty ($2.44bn) Retków‑Grodziszcze mine and Legnica smelter conversion, unlocking faster permitting, streamlined administration and access to preferential financing. Retków‑Grodziszcze is planned to deliver over 100 million tonnes of ore by 2055, yielding about 1.5 million tonnes of copper and 5,000 tonnes of silver, while Legnica’s recycling line targets 135,000 tonnes of electrolytic copper and 250 tonnes of nickel per year. The move materially boosts EU copper and nickel recycling capacity, central to the CRMA’s 25% recycling target.

    Related Industries & Products

    Mining

    Geotechnical software solutions for mining operations including CMRR analysis, hydrogeological testing, and data management.

    CMRR-io

    Streamline coal mine roof stability assessments with our cloud-based CMRR software featuring automated calculations, multi-scenario analysis, and collaborative workflows.

    HYDROGEO-io

    Comprehensive hydrogeological testing platform for managing, analysing, and reporting on packer tests, lugeon values, and hydraulic conductivity assessments.

    GEODB-io

    Centralised geotechnical data management solution for storing, accessing, and analysing all your site investigation and material testing data.

    AllGeotechnicalInfrastructureHazardsEnvironmental