Canada’s critical minerals capital gap: project economics lens for mine planners
Reviewed by Joe Ashwell
First reported on MINING.com
30 Second Briefing
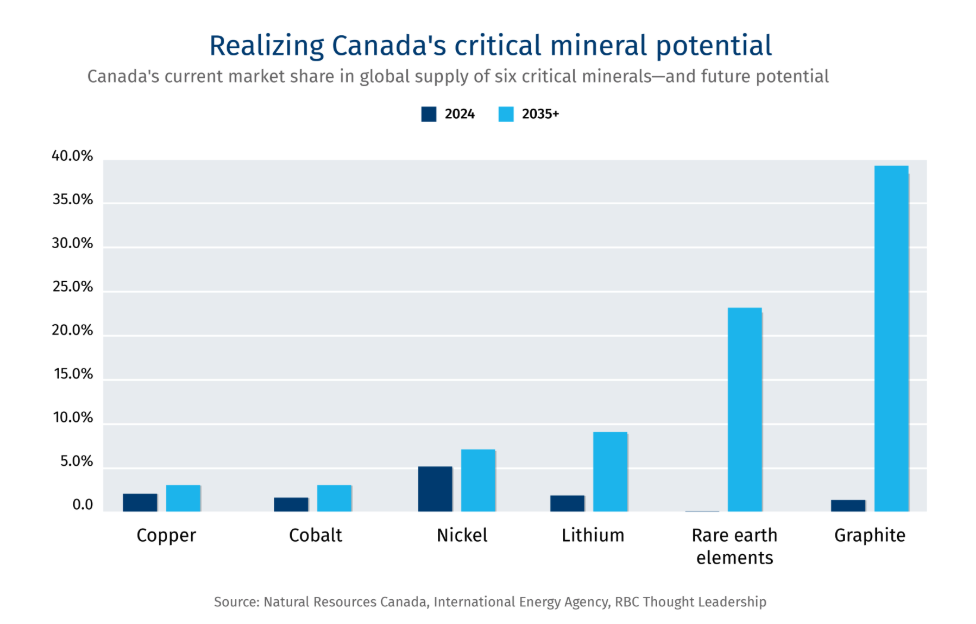
Canada has directed only 11% of more than C$700 billion in mining capital since 2000 into critical minerals, leaving it with just 2% of global output despite 67 projects worth C$72.4 billion planned or under way and the potential to reach 14% share if all proceed. Structural barriers include a C$20–C$30 million funding gap between feasibility and FID, permitting timelines exceeding five years, and reliance on a single copper smelter at Glencore’s Horne complex, forcing most concentrates to China, which controls about 70% of global refining capacity. RBC points to sovereign co-investment, mineral corridors in regions such as Quebec’s lithium belt and Sudbury, and infrastructure co-funding that can cut break-even prices by 22–24%—including up to C$2.4 billion needed for Ontario’s Ring of Fire—as key levers to unlock projects.
Technical Brief
- Canada has raised over C$700 billion in mining equity and M&A since 2000, 70% into gold/precious metals.
- RBC compares this allocation with Australia, which has directed more than double Canada’s capital into critical minerals.
- Between 2005–2012, C$119 billion of Canadian base metals and steel assets shifted to foreign ownership, eroding domestic operators.
- Canada currently runs a single copper smelter–refinery chain at Glencore’s Horne complex in Rouyn‑Noranda, Quebec.
- With only one domestic smelter, most Canadian concentrates are exported as raw feed, primarily to Chinese refineries.
- China controls about 70% of global refining capacity for 19 of the 20 most critical minerals, backed by state capital and deliberate overcapacity.
Our Take
RBC has been a recurring voice in our mining coverage, from warning that copper project pipelines are too thin at record prices (Dec 2025 copper piece) to opining on a potential Rio Tinto–Glencore tie‑up, so its view that Canada’s critical minerals only capture 11% of domestic mining capital will likely be taken seriously by boards weighing copper, nickel and lithium allocations in Canada versus Australia or Latin America.
The data showing Canada could lift its share of global output in six key critical minerals from 2% to 14% over about 15 years if 67 projects proceed contrasts sharply with our broader mining corpus, where most growth stories are still gold‑weighted, underscoring that permitting timelines beyond five years are now a central strategic risk rather than a routine hurdle for Canadian base‑ and battery‑metal developers.
With China controlling about 70% of global refining capacity for 19 of the 20 most critical minerals and Washington’s Project Vault stockpile sized at $12 billion, the relatively modest C$2 billion Critical Minerals Sovereign Wealth Fund signals that Canadian projects in regions like Quebec’s lithium belt and the Ring of Fire will probably need blended financing with US or European strategic capital to reach FID at competitive breakeven prices.
Prepared by collating external sources, AI-assisted tools, and Geomechanics.io’s proprietary mining database, then reviewed for technical accuracy & edited by our geotechnical team.
Related Articles


Related Industries & Products
Mining
Geotechnical software solutions for mining operations including CMRR analysis, hydrogeological testing, and data management.
Construction
Quality control software for construction companies with material testing, batch tracking, and compliance management.
CMRR-io
Streamline coal mine roof stability assessments with our cloud-based CMRR software featuring automated calculations, multi-scenario analysis, and collaborative workflows.
HYDROGEO-io
Comprehensive hydrogeological testing platform for managing, analysing, and reporting on packer tests, lugeon values, and hydraulic conductivity assessments.
GEODB-io
Centralised geotechnical data management solution for storing, accessing, and analysing all your site investigation and material testing data.