Western tungsten price gap to China: supply and DFARS lens for mine planners
Reviewed by Tom Sullivan
First reported on MINING.com
30 Second Briefing
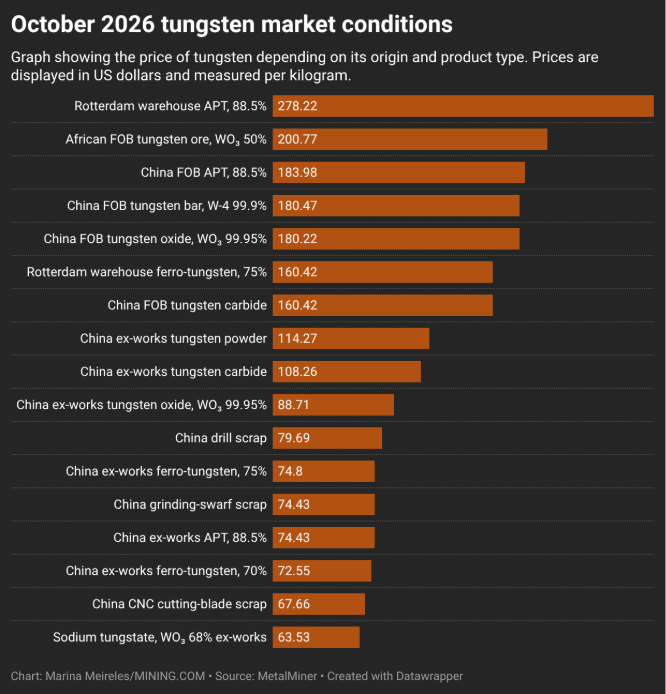
Western ammonium paratungstate (APT) prices have blown out to 3.74 times China’s, with Rotterdam warehouse APT at $278.22/kg in October versus $74.43/kg China ex-works, after China’s February 2025 export licensing and higher US tariffs fractured what was previously a 1.24x premium market. Since February 2025, Rotterdam APT has jumped from $34.60/kg to around $290/kg while China ex-works rose only to about $86/kg, and between March–September 2026 China prices fell 58% as Rotterdam rose 39%, confirming decoupled markets. For mining and downstream processors, the key constraints are now qualified, DFARS-compliant conversion capacity and traceable scrap within US and European supply chains ahead of the 1 January 2027 DFARS procurement restriction.
Technical Brief
- US tungsten tariffs increased from ~4% (2015–2024) to 16.2% in December 2025.
- A US scrap allocation order from late August 2026 keeps HTS‑classified tungsten scrap onshore.
- China’s February 2025 export licensing regime tightened outbound tungsten flows and strengthened its internal pricing power.
- Market separation only became pronounced from April 2026, after several months of post‑licensing adjustment.
- MetalMiner’s analysis uses pricing and structural indicators up to October 2026, with US data to August.
- Western tungsten constraints are now dominated by conversion capacity, not scrap availability, causing scrap stockpiling risk.
- DFARS procurement rules effective 1 January 2027 will further limit eligible tungsten origins for US defence contracts.
Our Take
With Rotterdam APT at roughly 3.7x China ex-works, European-facing projects like Abenójar Tungsten’s newly listed operation on the London Stock Exchange are positioned to capture unusually high regional premia if they can bring non-Chinese supply to market quickly.
The jump in US tungsten tariffs from about 4% to 16.2% by December 2025, combined with the widening Western–China price gap, implies that downstream US and EU defence contractors governed by DFARS will face sustained cost pressure unless new domestic or allied tungsten sources are developed.
Our database shows far fewer tungsten-focused pieces than for bulk commodities, so this extreme APT price divergence stands out within recent Mining coverage and is likely to sharpen investor interest in advanced tungsten projects relative to gold or base metals in the near term.
Prepared by collating external sources, AI-assisted tools, and Geomechanics.io’s proprietary mining database, then reviewed for technical accuracy & edited by our geotechnical team.
Related Articles


Related Industries & Products
Mining
Geotechnical software solutions for mining operations including CMRR analysis, hydrogeological testing, and data management.
CMRR-io
Streamline coal mine roof stability assessments with our cloud-based CMRR software featuring automated calculations, multi-scenario analysis, and collaborative workflows.
HYDROGEO-io
Comprehensive hydrogeological testing platform for managing, analysing, and reporting on packer tests, lugeon values, and hydraulic conductivity assessments.
GEODB-io
Centralised geotechnical data management solution for storing, accessing, and analysing all your site investigation and material testing data.