Juno Corp’s Ring of Fire bet: exploration scale and logistics lens for mine planners
Reviewed by Tom Sullivan
First reported on MINING.com
30 Second Briefing
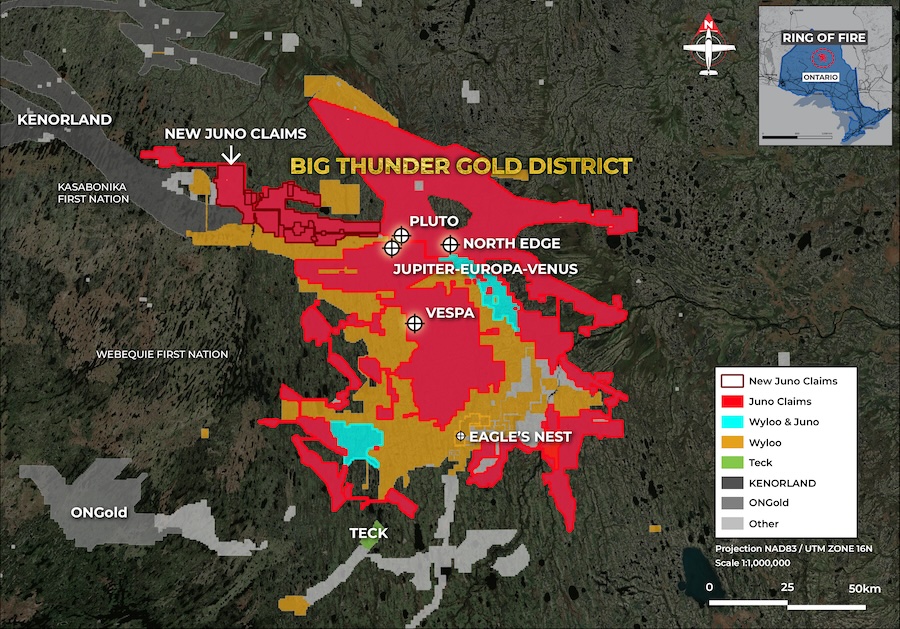
Juno Corp, led by founder and CEO Robert Cudney, is launching the largest exploration programme in more than a decade in Ontario’s Ring of Fire, controlling 29,956 claims over roughly 5,796 km²—just over half the camp—and anchored by the high‑grade Jupiter copper‑zinc‑silver VMS deposit. Cudney is renaming Northfield Capital as Juno International and has secured logistics by acquiring Sudbury-based True North Airways, while the company’s Big Thunder grassroots gold find has already earned the 2026 Bernie Schnieders Discovery of the Year Award. Veteran geologist John Harvey compares the camp’s long‑term potential to, and possibly exceeding, the Sudbury Basin and South Africa’s Bushveld Complex.
Technical Brief
- Juno controls 29,956 mineral claims over ~5,796 km², giving continuity along multiple geophysical trends.
- Land position exceeds 50% of the Ring of Fire camp, avoiding fragmented ownership during follow‑up drilling.
- Jupiter is a high‑grade VMS copper‑zinc‑silver deposit retained through the downturn as Juno’s core asset.
- Airborne and ground geophysics indicate at least three inner concentric “rings” with additional deposit potential.
- Acquisition of Sudbury-based True North Airways internalises air logistics, directly targeting high fly‑in exploration costs.
- Historical spend includes >US$500 million by Cleveland Cliffs on chromite before divestment to Noront for ~US$25 million.
Our Take
Juno Corp.’s control of just over 50% of the Ring of Fire camp comes as Ontario is committing C$140 million to road preparation and a C$500 million Critical Minerals Processing Fund, which in our coverage has materially improved the strategic value of early‑stage nickel, copper and chromite ground in the region.
The C$500 million Cleveland Cliffs spent on chromite in the Ring of Fire before selling to Noront for about C$25 million underscores how infrastructure and permitting risk can destroy value; the current Webequie Supply Road assessment process highlighted in our database is a key test of whether that risk profile is finally changing for new entrants like Juno Corp.
Wyloo’s push to advance the Eagle’s Nest nickel–copper–PGE deposit, noted in our recent Ring of Fire coverage, means Juno’s multi‑commodity exposure (nickel, copper, cobalt, PGMs and chromite) is likely to be benchmarked by investors against a more advanced, high‑grade underground development path rather than against the earlier, stalled chromite concepts pursued by Cliffs.
Prepared by collating external sources, AI-assisted tools, and Geomechanics.io’s proprietary mining database, then reviewed for technical accuracy & edited by our geotechnical team.
Related Articles


Related Industries & Products
Mining
Geotechnical software solutions for mining operations including CMRR analysis, hydrogeological testing, and data management.
Construction
Quality control software for construction companies with material testing, batch tracking, and compliance management.
CMRR-io
Streamline coal mine roof stability assessments with our cloud-based CMRR software featuring automated calculations, multi-scenario analysis, and collaborative workflows.
HYDROGEO-io
Comprehensive hydrogeological testing platform for managing, analysing, and reporting on packer tests, lugeon values, and hydraulic conductivity assessments.
GEODB-io
Centralised geotechnical data management solution for storing, accessing, and analysing all your site investigation and material testing data.