China’s rare earth giants’ profit surge: supply controls explained for project teams
Reviewed by Tom Sullivan
First reported on MINING.com
30 Second Briefing
China Northern Rare Earth and China Rare Earth Resources and Technology more than doubled net profits in the first nine months of 2026 to 3.65 billion yuan and 408 million yuan respectively, driven by tighter state supply controls and sharply higher prices. Neodymium-praseodymium (NdPr) compound prices have climbed 62% since the controls began, reaching 719,000 yuan per tonne, after Beijing cut production quota holders from six firms to two and extended quotas to imported feedstock in 2025. The strengthened quota regime and mandatory flow reporting tighten supply for magnet, battery and defence manufacturers, while reinforcing China’s leverage over US downstream projects still years from production.
Technical Brief
- Production quotas were cut from six companies to only CNRE and China Rare Earth Resources and Technology in 2024.
- In 2025, quota controls were extended to imported rare earth feedstock, not just domestic ore.
- Companies must now submit regular flow reports tracking strategic mineral movements through mining and processing stages.
- CNRE is identified as China’s largest light rare earth producer, centred on NdPr-bearing ores.
- China Rare Earth Resources and Technology focuses on heavy rare earths, which are typically scarcer and higher value.
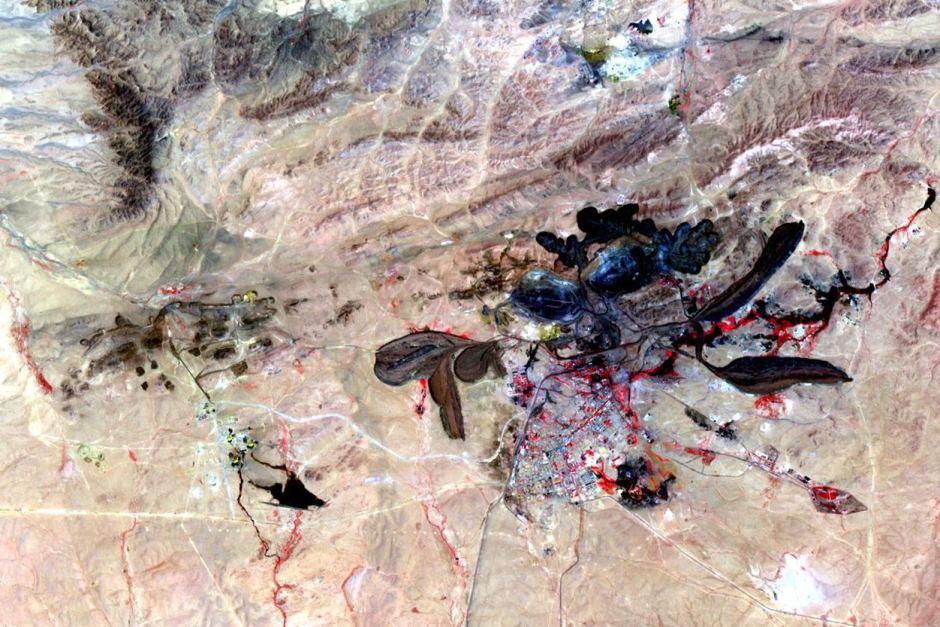
- Baiyun Ebo mine in Inner Mongolia supplies almost 50% of global rare earth output.
- China’s export controls specifically target several niche medium and heavy rare earths and associated permanent magnets.
- US critical mineral projects are described as “only on paper”, remaining several years from first production.
Our Take
The earlier April 2026 pricing move by China Northern Rare Earth Group to lift concentrate benchmarks by 44.6% already signalled tightening supply from Inner Mongolia, so the current profit jump largely reflects that higher-cost material and downstream users are now locked into a structurally higher NdPr cost base.
China’s consolidation of production quotas from six to two companies in 2024 effectively concentrates market power in China Northern Rare Earth and China Rare Earth Resources and Technology, which is likely to make it harder for non-Chinese rare earth projects to secure long-term offtake on terms that assume price softness.
The 100% consolidation of the Jameson Land Basin licences in Greenland, via the US$97 million Greenland Energy–80 Mile all-share deal, positions that asset as one of the relatively few non-Chinese rare earth options in our database, but the 62% NdPr price rise means new entrants will face both stronger project economics and higher political scrutiny from the USA and EU buyers.
Prepared by collating external sources, AI-assisted tools, and Geomechanics.io’s proprietary mining database, then reviewed for technical accuracy & edited by our geotechnical team.
Related Articles


Related Industries & Products
Mining
Geotechnical software solutions for mining operations including CMRR analysis, hydrogeological testing, and data management.
CMRR-io
Streamline coal mine roof stability assessments with our cloud-based CMRR software featuring automated calculations, multi-scenario analysis, and collaborative workflows.
HYDROGEO-io
Comprehensive hydrogeological testing platform for managing, analysing, and reporting on packer tests, lugeon values, and hydraulic conductivity assessments.
GEODB-io
Centralised geotechnical data management solution for storing, accessing, and analysing all your site investigation and material testing data.