Chile’s $111bn mining boom: lithium approvals and copper pipeline for project teams
Reviewed by Joe Ashwell
First reported on MINING.com
30 Second Briefing
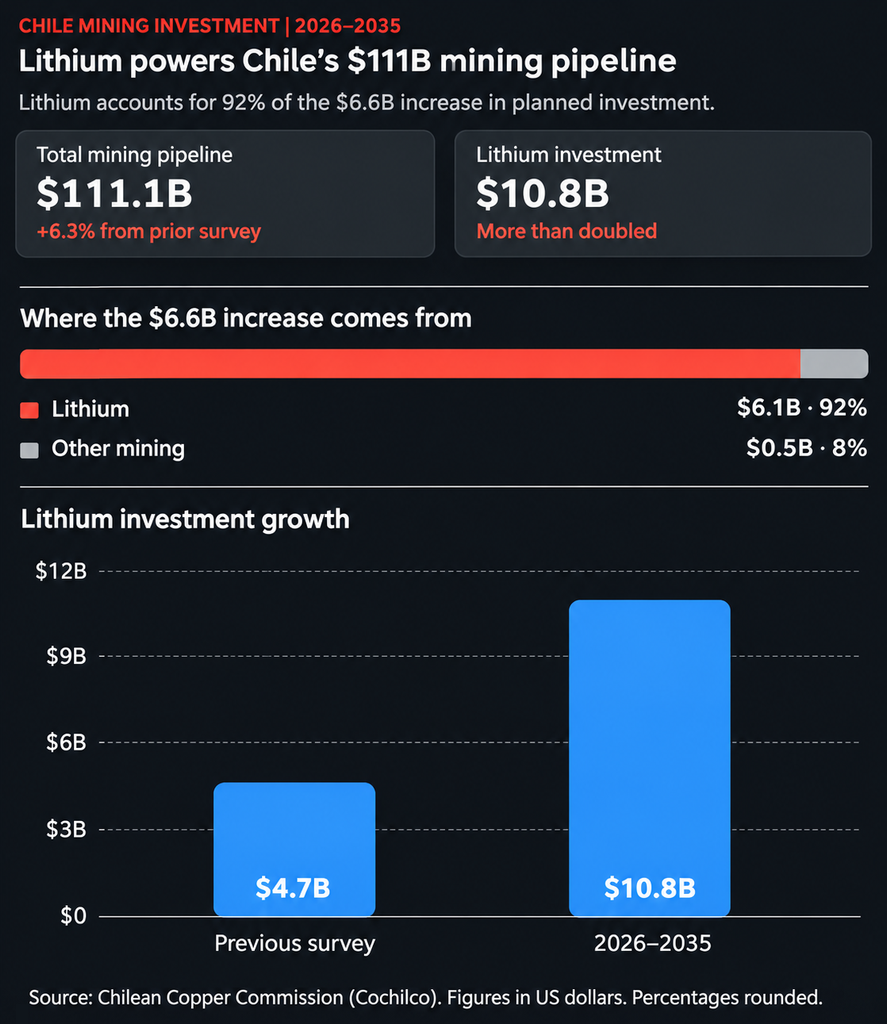
Chile’s mining investment pipeline has climbed to $111.1 billion for 2026–2035, with lithium projects doubling to $10.8 billion and two DLE-based schemes — Albemarle’s $3.1‑billion conversion and the $3‑billion Salar Futuro JV between Codelco and SQM — now awaiting SEA environmental approval. Copper still dominates at $93.9 billion, including BHP’s $1.3‑billion Escondida leaching extension to sustain 210,000 t/y cathode output and Capstone’s $500‑million Mantos Blancos upgrade to 9.8 Mt/y sulphide throughput. Antofagasta alone hosts $51.5 billion of projects, intensifying pressure on housing, services and transport corridors such as the Capricorn Bioceanic Corridor.
Technical Brief
- Cochilco’s updated portfolio covers 72 mining projects for 2026–2035, up from 59 previously.
- Lithium accounted for $6.1 billion of the $6.6‑billion portfolio increase between surveys, dominating incremental growth.
- Albemarle’s $3.1‑billion DLE transition is designed to nearly double lithium recovery versus its current operation.
- The Salar Futuro JV at Salar de Atacama targets 2031–2060 operations using DLE while extracting less brine.
- Both Albemarle’s conversion and Salar Futuro remain under SEA environmental review, gating construction and contracting timelines.
- Antofagasta region holds $51.5 billion of projects, ~46% of national pipeline, with copper schemes totalling $45 billion.
- More than 50% of Antofagasta’s mining workforce resides outside the region, stressing fly‑in/fly‑out logistics and camp capacity.
Our Take
SQM and Albemarle both feature heavily across our recent lithium coverage, including Chile’s mid‑2026 export surge and SQM’s Mt Holland expansion in Australia, signalling that decisions on Salar de Atacama and the $10.8 billion Chilean lithium pipeline will shape not just Chilean output but their global portfolio balance between brine and hard‑rock supply.
The projected 3.55 million tonnes LCE global supply by 2035, set against Chile’s $6.1 billion in lithium projects under environmental review, implies that prolonged SEA approvals could see Argentina or Australian spodumene projects (like Finniss and Mt Holland in our database) capture marginal demand that might otherwise have gone to Chilean brines and DLE conversions.
With copper still accounting for 84.5% of Chile’s planned mining spend and major brownfield work at Escondida and Mantos Blancos, operators in Antofagasta face a dual constraint: any delay in lithium approvals risks undercutting Chile’s diversification narrative while the region already relies on an external workforce share above 50%, tightening labour and infrastructure planning for both copper and lithium build‑outs.
Prepared by collating external sources, AI-assisted tools, and Geomechanics.io’s proprietary mining database, then reviewed for technical accuracy & edited by our geotechnical team.
Related Articles

Related Industries & Products
Mining
Geotechnical software solutions for mining operations including CMRR analysis, hydrogeological testing, and data management.
Construction
Quality control software for construction companies with material testing, batch tracking, and compliance management.
CMRR-io
Streamline coal mine roof stability assessments with our cloud-based CMRR software featuring automated calculations, multi-scenario analysis, and collaborative workflows.
HYDROGEO-io
Comprehensive hydrogeological testing platform for managing, analysing, and reporting on packer tests, lugeon values, and hydraulic conductivity assessments.
GEODB-io
Centralised geotechnical data management solution for storing, accessing, and analysing all your site investigation and material testing data.