Beaver Creek gold bond break: capital flows and project signals for mine planners
Reviewed by Joe Ashwell
First reported on MINING.com
30 Second Briefing
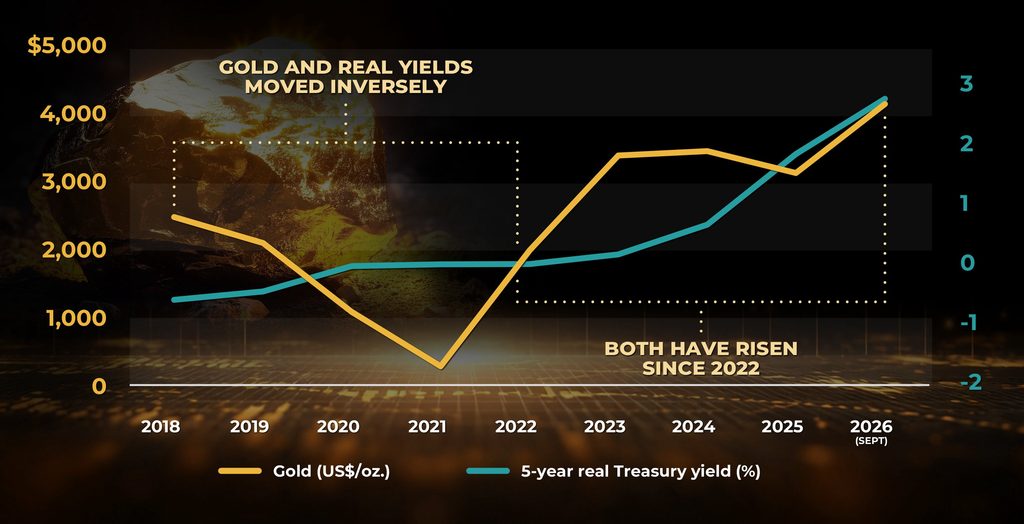
Gold’s decoupling from rising US real Treasury yields since March 2022, with front‑month COMEX futures peaking at US$5,318/oz and 10‑year yields touching 5.2%, is driving central banks to keep buying on dips (863 tonnes net in 2025) and reviving gold’s perceived monetary role. Yet S&P data show 2025 global gold exploration budgets of US$6.15 billion still favour near‑mine work (over 50% of spend) and late‑stage projects, leaving grassroots with a record‑low 18%. Select juniors with advanced assets, such as Amarc Resources’ C$20‑million and Banyan Gold’s C$58‑million raises, are attracting institutions, but broad generalist capital remains focused on large, liquid producers.
Technical Brief
- Central banks bought 863 tonnes of gold in 2025, versus a 2010–21 average of 473 tonnes.
- Incrementum estimates the global bond market at US$140 trillion versus US$14 trillion in investment gold.
- A 2% capital rotation from bonds would equal nearly US$3 trillion, about 20% of investable gold.
- Global gold exploration budgets reached US$6.15 billion in 2025, with majors spending US$3.5 billion.
- Grassroots exploration captured a record‑low 18% of budgets, with over half directed to near‑mine work.
- Amarc Resources secured a fully subscribed C$20‑million private placement from large Canadian and U.S. institutions.
- Banyan Gold lifted its treasury to ~C$75 million, then announced a further C$58‑million raise.
- Meridian Mining still must secure US$377 million of project finance for the Cabaçal copper‑gold project in Brazil.
- Producers in the NYSE Arca Gold Miners Index trade at 5.1× EV/EBITDA versus 15× for the equal‑weighted S&P 500.
- Liquidity constraints mean many generalist funds cannot deploy meaningful positions into ~C$50‑million juniors despite sectoral underinvestment.
Our Take
The valuation gap highlighted here for NYSE Arca Gold Miners versus the S&P 500 mirrors what our database shows across other Sprott-linked coverage: capital is still chasing copper and uranium thematic funds more aggressively than traditional gold equities, even with bullion near records.
With majors accounting for 57% of the US$6.15 billion 2025 gold exploration budget, juniors like Banyan Gold and Amarc Resources are likely to rely heavily on strategic investors and royalties/streams (e.g., Franco-Nevada) rather than expecting majors to fund early-stage risk directly.
Meridian Mining’s need to secure US$377 million for the Cabaçal copper-gold project comes as our recent copper pieces show tightening mined supply and strong prices, which could improve project economics but also raise capex and operating cost assumptions that lenders will scrutinise closely.
Prepared by collating external sources, AI-assisted tools, and Geomechanics.io’s proprietary mining database, then reviewed for technical accuracy & edited by our geotechnical team.
Related Articles


Related Industries & Products
Mining
Geotechnical software solutions for mining operations including CMRR analysis, hydrogeological testing, and data management.
CMRR-io
Streamline coal mine roof stability assessments with our cloud-based CMRR software featuring automated calculations, multi-scenario analysis, and collaborative workflows.
HYDROGEO-io
Comprehensive hydrogeological testing platform for managing, analysing, and reporting on packer tests, lugeon values, and hydraulic conductivity assessments.
GEODB-io
Centralised geotechnical data management solution for storing, accessing, and analysing all your site investigation and material testing data.