Zijin’s $4B Allied Gold deal delay: asset and jurisdiction risks for mine planners
Reviewed by Tom Sullivan
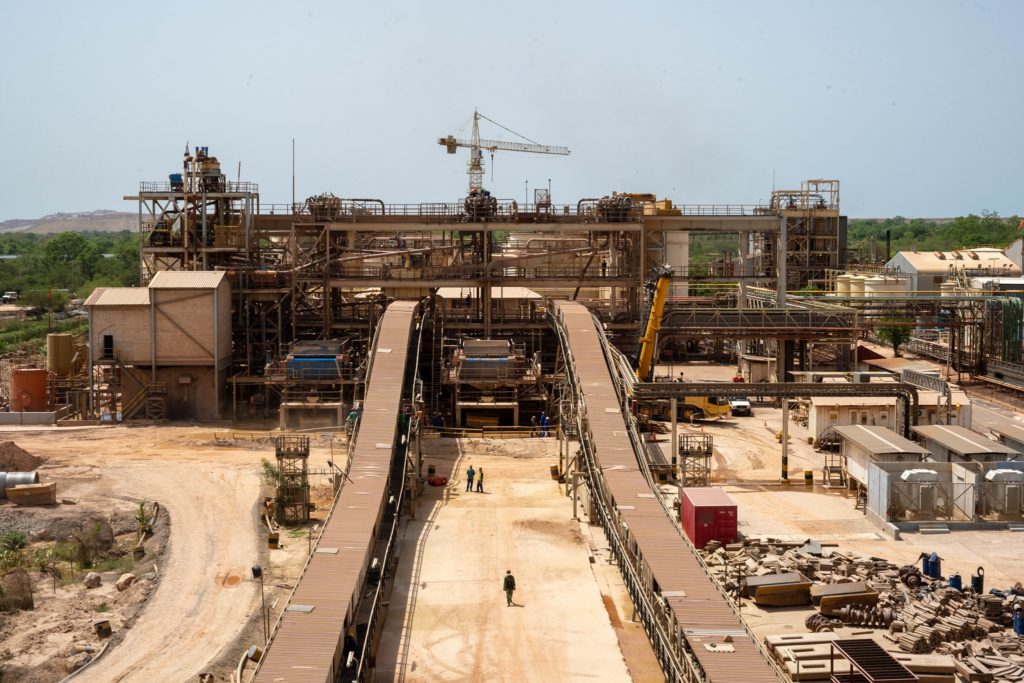
First reported on MINING.com
30 Second Briefing
Zijin Gold’s proposed C$5.5 billion (about $4 billion) cash acquisition of Allied Gold is facing delays at China’s National Development and Reform Commission, which is questioning the roughly 5% premium and jurisdictional risks tied to Allied’s African assets. The deal would add the Sadiola mine in Mali, a large Côte d’Ivoire complex and the Kurmuk project in Ethiopia, with the first two delivering nearly 380,000 oz of gold in 2025 and Kurmuk due to pour first gold this year. Allied’s market value sits around C$4.4 billion and the outside closing date has been pushed to end-July.
Technical Brief
- Zijin’s offer is structured as an all‑cash C$5.5 billion transaction following its Hong Kong spin‑out.
- Chinese National Development and Reform Commission review is focused on valuation discipline and host‑country risk allocation.
- Mali contributes roughly 50% of Allied’s gold output, concentrating geopolitical and security exposure in one jurisdiction.
- Allied’s Côte d’Ivoire operations are described as a “large mining complex”, implying multi‑pit or hub‑and‑spoke processing.
- Kurmuk in Ethiopia is classed as near‑production, with first gold targeted within the current calendar year.
- Allied’s 2025 production from Sadiola and Côte d’Ivoire exceeded internal forecasts, indicating upside against original technical studies.
- Market capitalisation of about C$4.4 billion versus the C$5.5 billion bid underpins regulator concerns over the premium.
- Share price dropped ~6.5% on the delay news, signalling perceived execution and political‑risk discount by equity markets.
- Canadian and relevant African regulators have already cleared the deal, leaving Chinese outbound‑investment approval as the gating item.
Our Take
Our database shows that once completed, the Allied Gold deal would hand Zijin Mining Group immediate control of the Sadiola mine in Mali and the Bonikro–Agbaou complex in Côte d’Ivoire, giving it a multi-asset African gold platform rather than a single-country exposure.
Zijin’s concurrent move to lift its stake in Chifeng Jilong Gold Mining, alongside the proposed Allied Gold acquisition, signals a strategy of consolidating gold positions across both China and Africa at a time when many of the 1182 Mining stories in our coverage focus on single-asset growth plays instead.
Allied Gold’s recent Phase 1 expansion at Sadiola and new targets at the Kurmuk project in Ethiopia mean any prolonged regulatory delay in China risks freezing value-accretive workstreams at a point when the assets are transitioning from discovery and expansion into higher-output operation.
Prepared by collating external sources, AI-assisted tools, and Geomechanics.io’s proprietary mining database, then reviewed for technical accuracy & edited by our geotechnical team.
Related Articles


Related Industries & Products
Mining
Geotechnical software solutions for mining operations including CMRR analysis, hydrogeological testing, and data management.
CMRR-io
Streamline coal mine roof stability assessments with our cloud-based CMRR software featuring automated calculations, multi-scenario analysis, and collaborative workflows.
HYDROGEO-io
Comprehensive hydrogeological testing platform for managing, analysing, and reporting on packer tests, lugeon values, and hydraulic conductivity assessments.
GEODB-io
Centralised geotechnical data management solution for storing, accessing, and analysing all your site investigation and material testing data.