Glencore-backed PG West drilling: Ballywire grades and scale explained for mine teams
Reviewed by Joe Ashwell
First reported on MINING.com
30 Second Briefing
New drilling at Group Eleven Resources’ PG West project in Ireland has extended high-grade mineralisation at the Ballywire discovery, with hole 26-3552-57 cutting 62.5 m from 329 m depth grading 2.9% Zn, 2.7% Pb and 25 g/t Ag, including 11.8 m at 3.3% Zn, 10.1% Pb and 45 g/t Ag. Backed by C$12 million raised in March from investors including Glencore (13% stake) and Michael Gentile (14%), the company has expanded its PG West drilling campaign from 20,000 m to 67,000–75,000 m using four rigs. Mineralisation comprises sphalerite, galena and pyrite with local chalcopyrite and suspected tennantite-tetrahedrite, now traced along a ~1.5 km massive sulphide corridor.
Technical Brief
- Hole 25-3552-53 intersected 6.6 m from 390 m depth grading 0.13% Zn, 0.19% Pb, 29.8 g/t Ag.
- Hole 25-468-22 returned 11 m from ~336 m depth at 0.53% Zn, 0.21% Pb, 1.2 g/t Ag.
- Mineralisation assemblage dominated by sphalerite, galena and pyrite, with local chalcopyrite and suspected tennantite–tetrahedrite.
- Ballywire discovery announced September 2022; 79 drillholes completed and reported there to date.
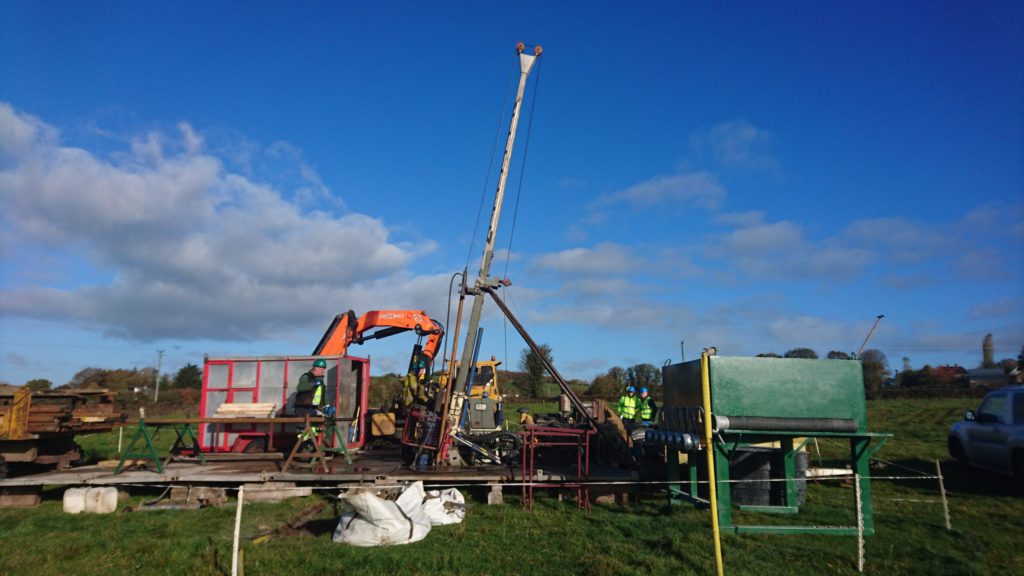
- Four diamond rigs are currently operating at Ballywire, indicating continuous, high-intensity step-out and infill drilling.
- Ballywire lies ~20 km from Stonepark and ~200 km southwest of Dublin within the Irish zinc district.
- PG West remains at an exploration stage with no mineral resource estimate yet, unlike Stonepark and Ballinalack.
- Glencore holds ~13% of Group Eleven; Michael Gentile holds ~14% and stakes in 25+ TSX-V juniors.
- Market capitalisation sits around C$307 million at C$1.09/share, providing funding headroom for extended drilling.
Our Take
Glencore’s 13% stake in Group Eleven sits alongside its exposure to large copper and coal assets in Colombia and Argentina in our coverage, signalling that the major is keeping a foothold in smaller zinc-lead plays even as it manages late‑life closures like Cerrejón and pursues big-ticket copper growth.
Within our zinc- and lead-tagged database, Ireland’s district appears far less frequently than Andean or US projects, so the Ballywire and Stonepark work gives Glencore and other operators diversification away from the more politically volatile jurisdictions highlighted in recent Peru and Argentina pieces.
The 1.5 km high‑grade corridor at Ballywire being drilled with four rigs suggests Group Eleven is already in a resource‑definition mindset; at the grades reported, this could position the Irish zinc district as a relatively low‑tonnage but high‑margin complement to Glencore’s larger base‑metal portfolio if continuity holds up along strike.
Prepared by collating external sources, AI-assisted tools, and Geomechanics.io’s proprietary mining database, then reviewed for technical accuracy & edited by our geotechnical team.
Related Articles


Related Industries & Products
Mining
Geotechnical software solutions for mining operations including CMRR analysis, hydrogeological testing, and data management.
CMRR-io
Streamline coal mine roof stability assessments with our cloud-based CMRR software featuring automated calculations, multi-scenario analysis, and collaborative workflows.
HYDROGEO-io
Comprehensive hydrogeological testing platform for managing, analysing, and reporting on packer tests, lugeon values, and hydraulic conductivity assessments.
GEODB-io
Centralised geotechnical data management solution for storing, accessing, and analysing all your site investigation and material testing data.