Diesel price surge putting mining profits to test: cost control lessons for planners
Reviewed by Joe Ashwell
First reported on MINING.com
30 Second Briefing
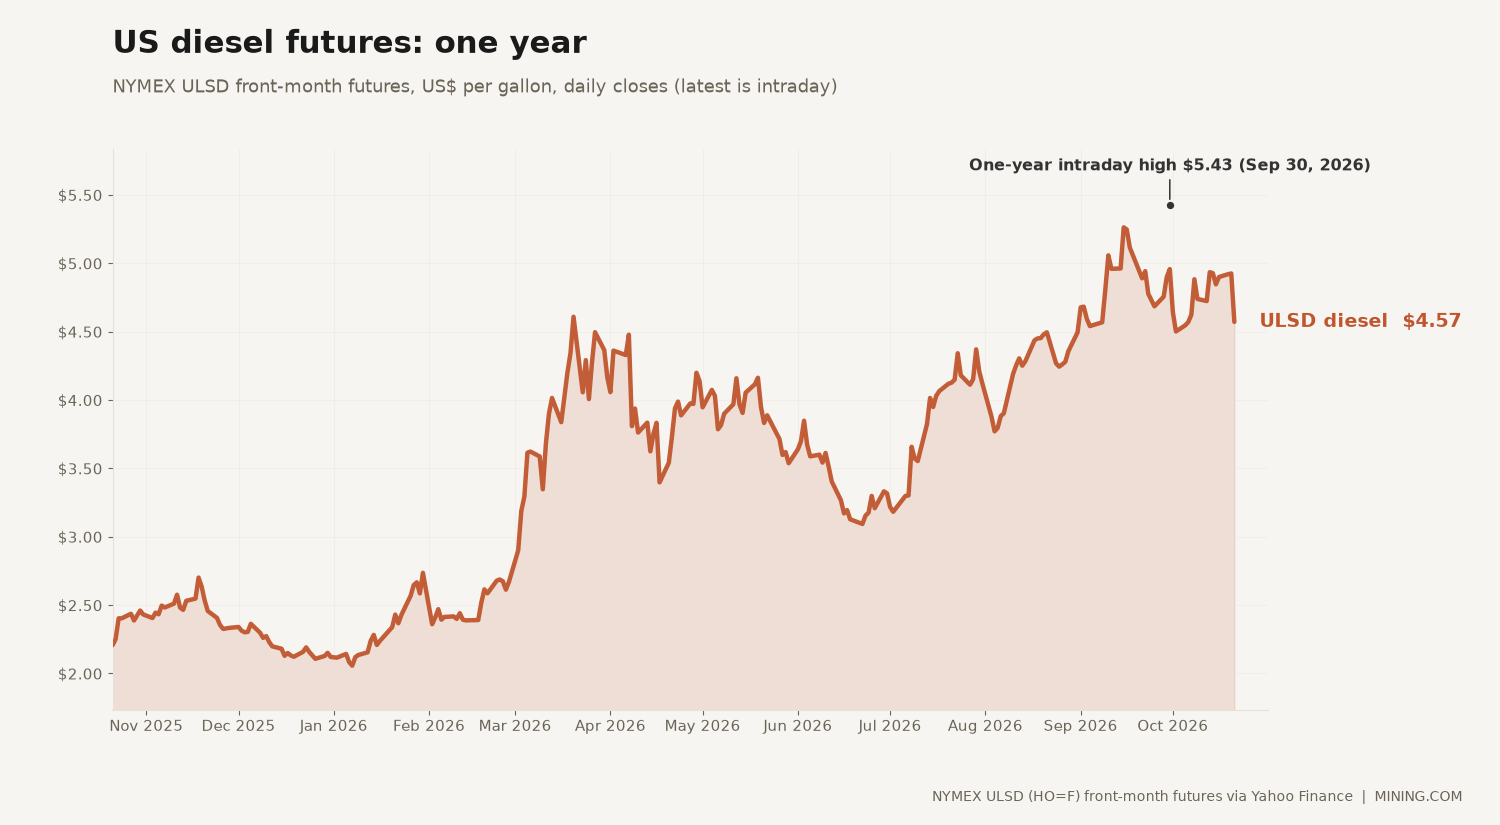
Soaring diesel prices linked to disrupted oil and LNG flows through the Strait of Hormuz are driving sharp cost increases across mines, with TD Cowen projecting a 15% year-on-year rise in AISC and 22% higher all‑in costs, and Antofagasta lifting copper cash cost guidance to $2.60–$2.70/lb. Capstone’s Mantos Blancos C1 costs jumped 88% to $3.93/lb, with about $0.34/lb from diesel, while Barrick’s gold production cost rose 17% yet Q2 2026 EBITDA still climbed 51% to $2.55 billion on record bullion prices. Ivanhoe’s Kamoa‑Kakula smelter and sulphuric acid sales, plus by‑product credits at Mantoverde, show integrated processing and diversification can partially hedge fuel inflation as metal prices start to soften.
Technical Brief
- Monument’s Selinsing mine saw unit mining costs rise by US$0.57 per tonne from diesel alone.
- At Mantos Blancos, Capstone attributes about US$0.34/lb of its C1 cost to higher diesel.
- Mantoverde’s diesel inflation added US$0.23/lb, but gold by-product credits still cut C1 by 16%.
- Ivanhoe’s Kamoa-Kakula smelter reportedly had its operating costs fully covered by sulphuric acid sales.
- Kinross’ production cost of sales climbed 25% year-on-year to US$1,352/oz, mainly from fuel.
- Monument’s Selinsing production cost jumped from US$814/oz to US$1,243/oz, exceeding a 50% increase.
- Newmont estimates every US$10/bbl oil increase adds US$110 million, or US$21/oz, to costs.
- World Gold Council noted diesel prices up 54% in the US, and nearly 100% in Australia.
- Rio Tinto is exploiting shorter shipping distances to Asia to reduce fuel exposure versus Latin American/African exporters.
Our Take
Antofagasta’s higher 2027 copper cash cost guidance in the 15 October piece sits alongside the diesel-driven increases flagged here, suggesting its margin risk is now being hit from both energy inputs and softer production guidance rather than just one-off fuel volatility.
In our database of 1269 Mining stories, diesel and LNG appear far less frequently as lead cost drivers than labour or grade decline, so the explicit oil-price sensitivities disclosed by Newmont and others here are likely to sharpen how analysts model energy exposure across gold and copper names.
Ivanhoe Mines’ Kamoa-Kakula complex, which already features in several copper-price and supply stories in our coverage, now looks doubly exposed: high EBITDA leverage to copper prices on the upside, but also material downside sensitivity to diesel and power costs in the DRC where grid reliability is uneven.
Prepared by collating external sources, AI-assisted tools, and Geomechanics.io’s proprietary mining database, then reviewed for technical accuracy & edited by our geotechnical team.
Related Articles


Related Industries & Products
Mining
Geotechnical software solutions for mining operations including CMRR analysis, hydrogeological testing, and data management.
CMRR-io
Streamline coal mine roof stability assessments with our cloud-based CMRR software featuring automated calculations, multi-scenario analysis, and collaborative workflows.
HYDROGEO-io
Comprehensive hydrogeological testing platform for managing, analysing, and reporting on packer tests, lugeon values, and hydraulic conductivity assessments.
GEODB-io
Centralised geotechnical data management solution for storing, accessing, and analysing all your site investigation and material testing data.